Modelo 720 for Expats: Who Files, Thresholds and Penalties
Got a bank account or property back home? Modelo 720 is the annual return on assets held abroad, filed by Spanish tax residents. You report a block of accounts, securities or property when it exceeds €50,000. File online between 1 January and 31 March of the following year.
Also in: Deutsch
On this page
Just became a Spanish tax resident and still own accounts or a flat back home? Modelo 720 is the information return on assets held abroad. It does not add tax by itself; it tells the Tax Agency what you own outside Spain, and errors are penalised. Read the tax residency guide first if you are unsure you count as resident.
Who has to file?
Tax residents file it. Individuals resident in Spanish territory are among those obliged to file Modelo 720, meaning all taxpayers who pay IRPF on their entire income. A Spanish tax resident is taxed on worldwide income.
The duty also covers people who held, were authorised on or controlled foreign accounts at any time in the year, even if they no longer did at 31 December.
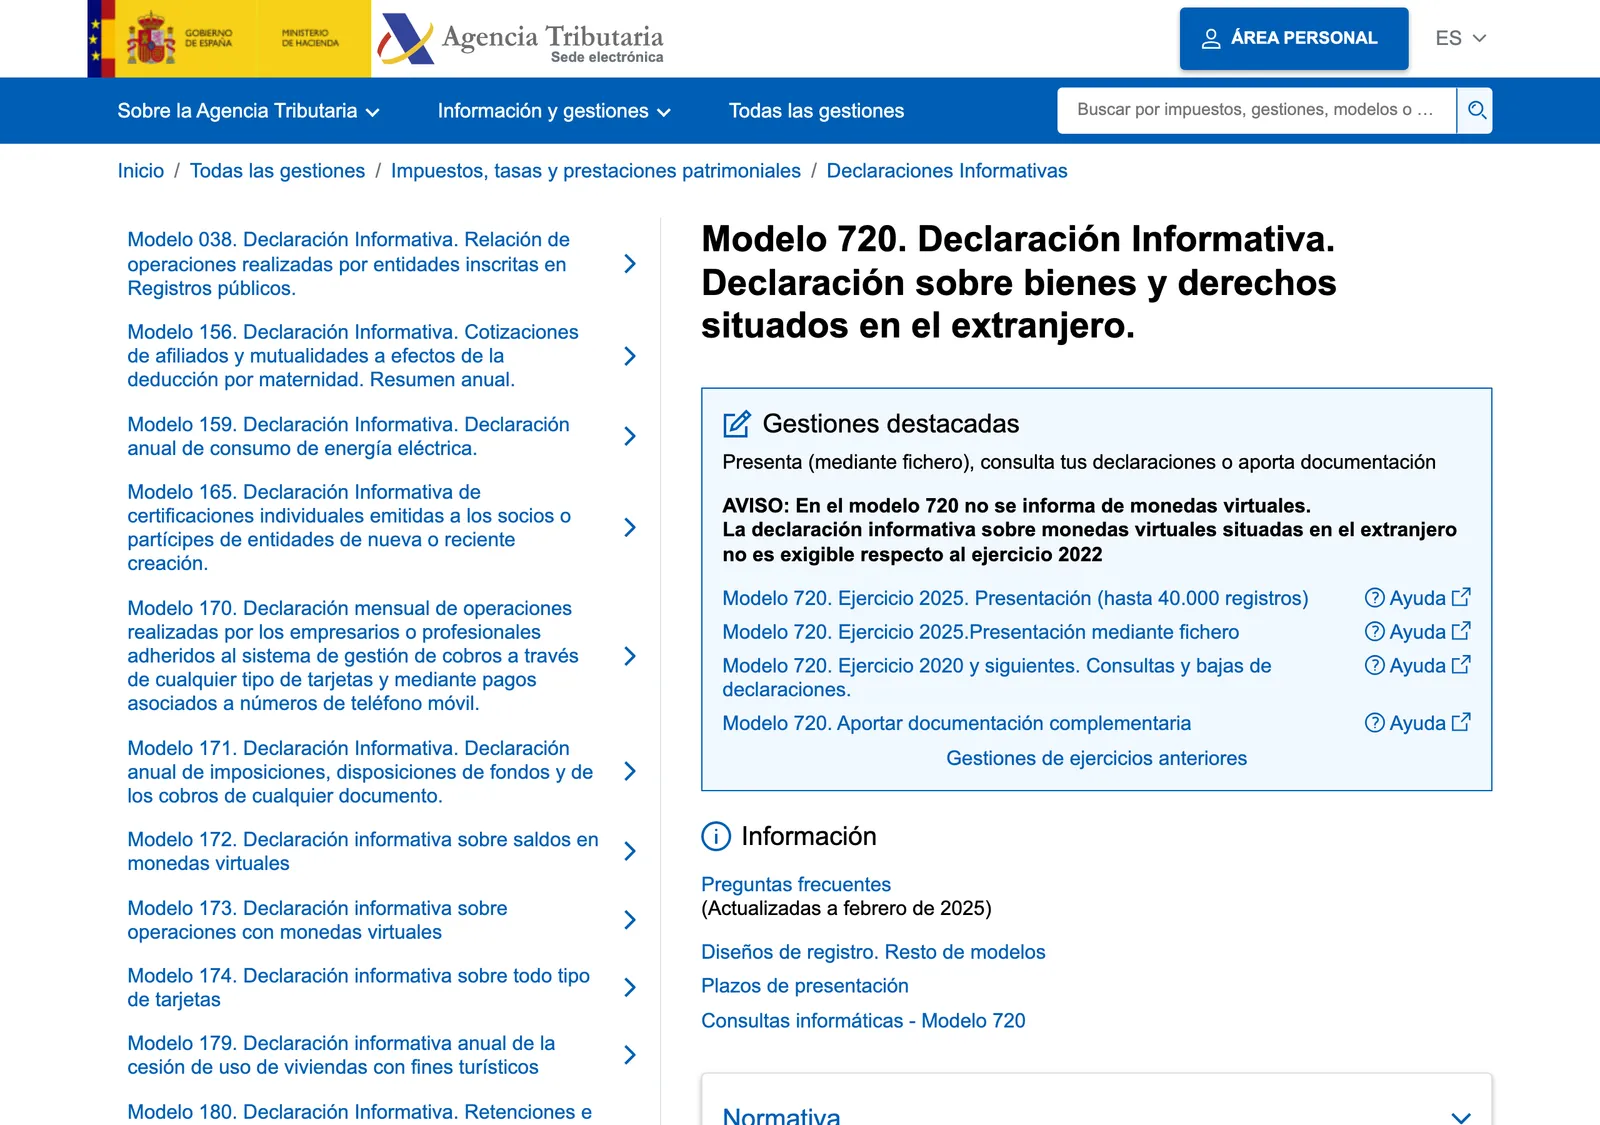
What goes into the three blocks
Modelo 720 has three information duties, and each is judged on its own, so test them block by block.
- Accounts. Foreign bank accounts you own, benefit from, are authorised on or control.
- Securities and insurance. Securities, shares, funds and similar rights held abroad, plus foreign life and disability insurance and annuities.
- Real estate. Real estate and real-estate rights you own abroad.
Virtual currencies are not reported in Modelo 720. A separate return, Modelo 721, covers virtual currencies located abroad.
The €50,000 limits
Above the limit you report everything in that block, not only the excess.
| Block | Limit | Refile if it rose by more than |
|---|---|---|
| Foreign accounts | €50,000 | €20,000 |
| Securities, funds, insurance | €50,000 | €20,000 |
| Foreign real estate | €50,000 | €20,000 |
For accounts, both the 31 December balances and the average balances of the last quarter are tested against €50,000. For real estate, the return states the acquisition value.
The €20,000 rise is not the only trigger. You must also file for an account you closed or stopped being authorised on during the year, and for securities or property you no longer owned at 31 December.
Deadline and how to file
The return is filed between 1 January and 31 March of the year after the year it reports.
se realizará entre el 1 de enero y el 31 de marzo del año siguiente a aquel al que se refiera la información a suministrar.
will be made between 1 January and 31 March of the year following the one to which the information to be supplied refers.
BOE · Order approving Modelo 720, art. 7
- Gather the 31 December data for each account, security and property before the period opens.
- Decide block by block whether the €50,000 limit is exceeded.
- File online, on the Tax Agency’s procedure page for Modelo 720.
- File between 1 January and 31 March.
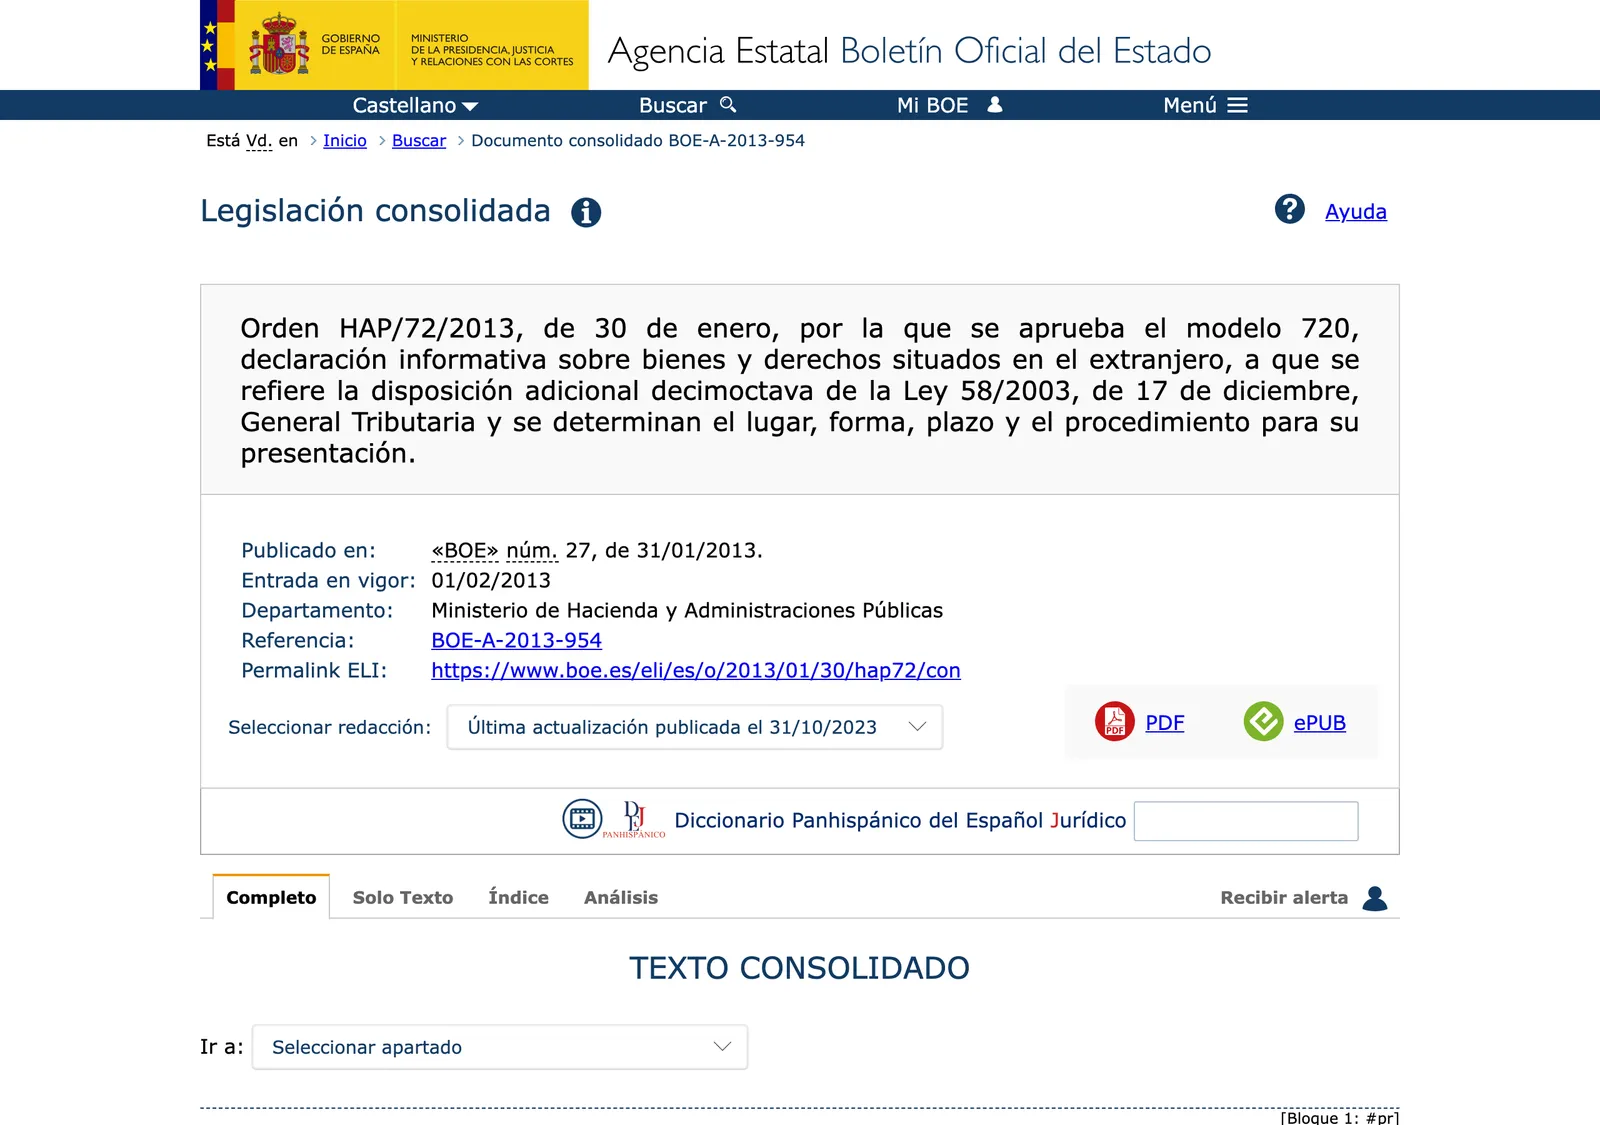
In the latest published campaign the period ran from 1 January to 31 March 2026.
What happens if you get it wrong?
The old special penalty regime for Modelo 720 is gone. A 2022 reform changed the rules after the Court of Justice of the European Union judgment of 27 January 2022. Penalties depend on the type of failure.
Si se trata de declaraciones exigidas con carácter general en cumplimiento de la obligación de suministro de información recogida en los artículos 93 y 94 de esta ley, la sanción consistirá en multa pecuniaria fija de 20 euros por cada dato o conjunto de datos referidos a una misma persona o entidad que hubiera debido incluirse en la declaración con un mínimo de 300 euros y un máximo de 20.000 euros.
In the case of returns required generally in fulfilment of the information-supply obligation in articles 93 and 94 of this law, the penalty shall be a fixed fine of EUR 20 for each data item or data set relating to the same person or entity that should have been included in the return, with a minimum of EUR 300 and a maximum of EUR 20,000.
BOE · Ley 58/2003, art. 198.2
- Not filing. Treated as failing to file on time with no economic harm to the Treasury. A return of this general type that is late or missing is fined 20 euros per data item, with a minimum of 300 euros and a maximum of €20,000.
- Filing with errors. Treated under article 199. Without monetary data the fine is 200 euros per omitted, inexact or false data item. With monetary data it is up to 2 per cent of the amount wrongly declared, with a minimum of 500 euros.
- Each block counts alone. Penalties apply separately to each of the three duties.
Ask a gestor which penalty fits your return.
Beckham taxpayers, families and help in Valencia
Article 93 taxpayers are listed as not obliged to file Modelo 720. The regime does not extend to other family members, who may be subject to the duty to the extent they are tax resident in Spain. The Beckham law guide covers the regime.
With assets in more than one country, or a block close to its limit, book a gestor or asesor fiscal before the 31 March deadline. The Agencia Tributaria delegation for the city sits on Plaça de l’Ajuntament.
Placa de l'Ajuntament 9, 46002 Valencia, Spain · Open in Google Maps (opens in a new tab)
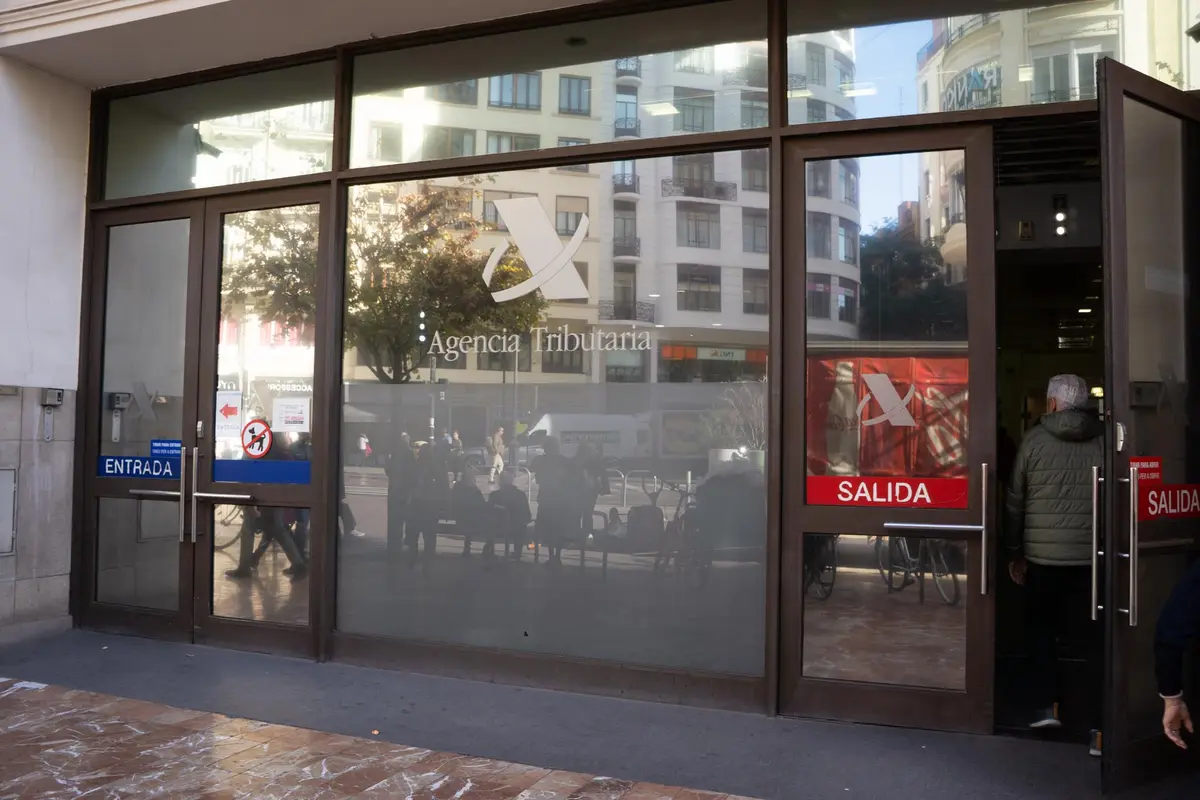
Photo credits
- A Valencia city square, shown for atmosphere: Wikimedia Commons (opens in a new tab), Zarateman (CC0)
- One of Valencia's old city gates, shown for atmosphere: Wikimedia Commons: Torres de Cuart DD 106 (opens in a new tab), Diego Delso (CC BY-SA 3.0)
- Photos and clips uploaded to Google Maps (Tax Agency office in Valencia on Google Maps (opens in a new tab)) by Robert Wilson.
Step by step
- Confirm you are a Spanish tax residentIndividuals resident in Spain who pay IRPF on their whole income are obliged.
- List your foreign assets at 31 DecemberAccounts, securities and insurance, and real estate abroad.
- Test each block against €50,000Each block is tested on its own; above the limit you report the whole block.
- File between 1 January and 31 MarchFile online in the period that follows the year being reported.
Not confirmed: Article 93 (Beckham) taxpayers are listed as not obliged to file Modelo 720. Confirm with a gestor before you rely on it, because the 2022 reform changed the penalty rules.
Reach readers planning life in Valencia. Advertise → hello@settlevalencia.com
Common questions
Do I have to file Modelo 720?
Yes, if you are a Spanish tax resident. Individuals resident in Spanish territory, meaning all taxpayers who pay IRPF on their entire income, are among those obliged. The duty applies to each block of assets above its limit. Check your status with the tax residency guide first.
What is the €50,000 threshold?
It is a limit per block. Each block has its own limit. Foreign accounts, foreign securities, funds and insurance, and foreign real estate are each tested against €50,000 combined. Above the limit you report everything in that block, not only the excess.
When do I have to file Modelo 720 again?
Once the first return is in, file a block again when its combined value has risen by more than €20,000 since the last return. Also file when you closed, sold or stopped holding an item already reported. Check the 31 December values every year.
What is the deadline and how do I file?
The return covers the previous year and is filed between 1 January and 31 March. It is filed online. Gather balances, values and acquisition values for 31 December before the period opens.
Do I report my crypto in Modelo 720?
No. Virtual currencies are not reported in Modelo 720. A separate return, Modelo 721, covers virtual currencies located abroad. Check which return applies before you file either one.
What are the penalties for missing it?
The penalty regime is the general one in articles 198 and 199 of the General Tax Law. A late or missing return of this type is fined 20 euros per data item, minimum 300 euros and maximum €20,000. Penalties apply to each block separately.
Is the old special penalty regime still in force?
No. A 2022 reform changed the regime to follow the Court of Justice of the European Union judgment of 27 January 2022. Penalties are now the general ones in articles 198 and 199.
My partner is under the Beckham regime. Do I have to file?
Possibly. The article 93 regime does not extend to other family members, who may be subject to the foreign-assets reporting duty to the extent they are tax resident in Spain. Each person's status is separate, so ask a gestor for the household.
Read next
General information checked against the sources listed above, not legal advice for your situation. Rules and office practice change; confirm with the immigration office or a licensed adviser before you act. See how guides are checked.
Spotted an error? Report it.