German Pension in Spain: Tax Under the Treaty (2026)
As a Spanish tax resident, you are taxed here on worldwide income, subject to the treaty. A pension paid by a German public body for public service is normally taxable only in Germany. A social-insurance pension is taxed in Spain; if first paid from 2015 to 2029, Germany may also take up to 5 per cent.
Also in: Deutsch
On this page
Moving to Valencia with a German pension? Who taxes it depends on who pays it. A civil-servant pension (Beamtenpension) follows one treaty article, and a social-insurance pension follows another. Your own tax figure is a job for a gestor.
Does Spain tax your German pension?
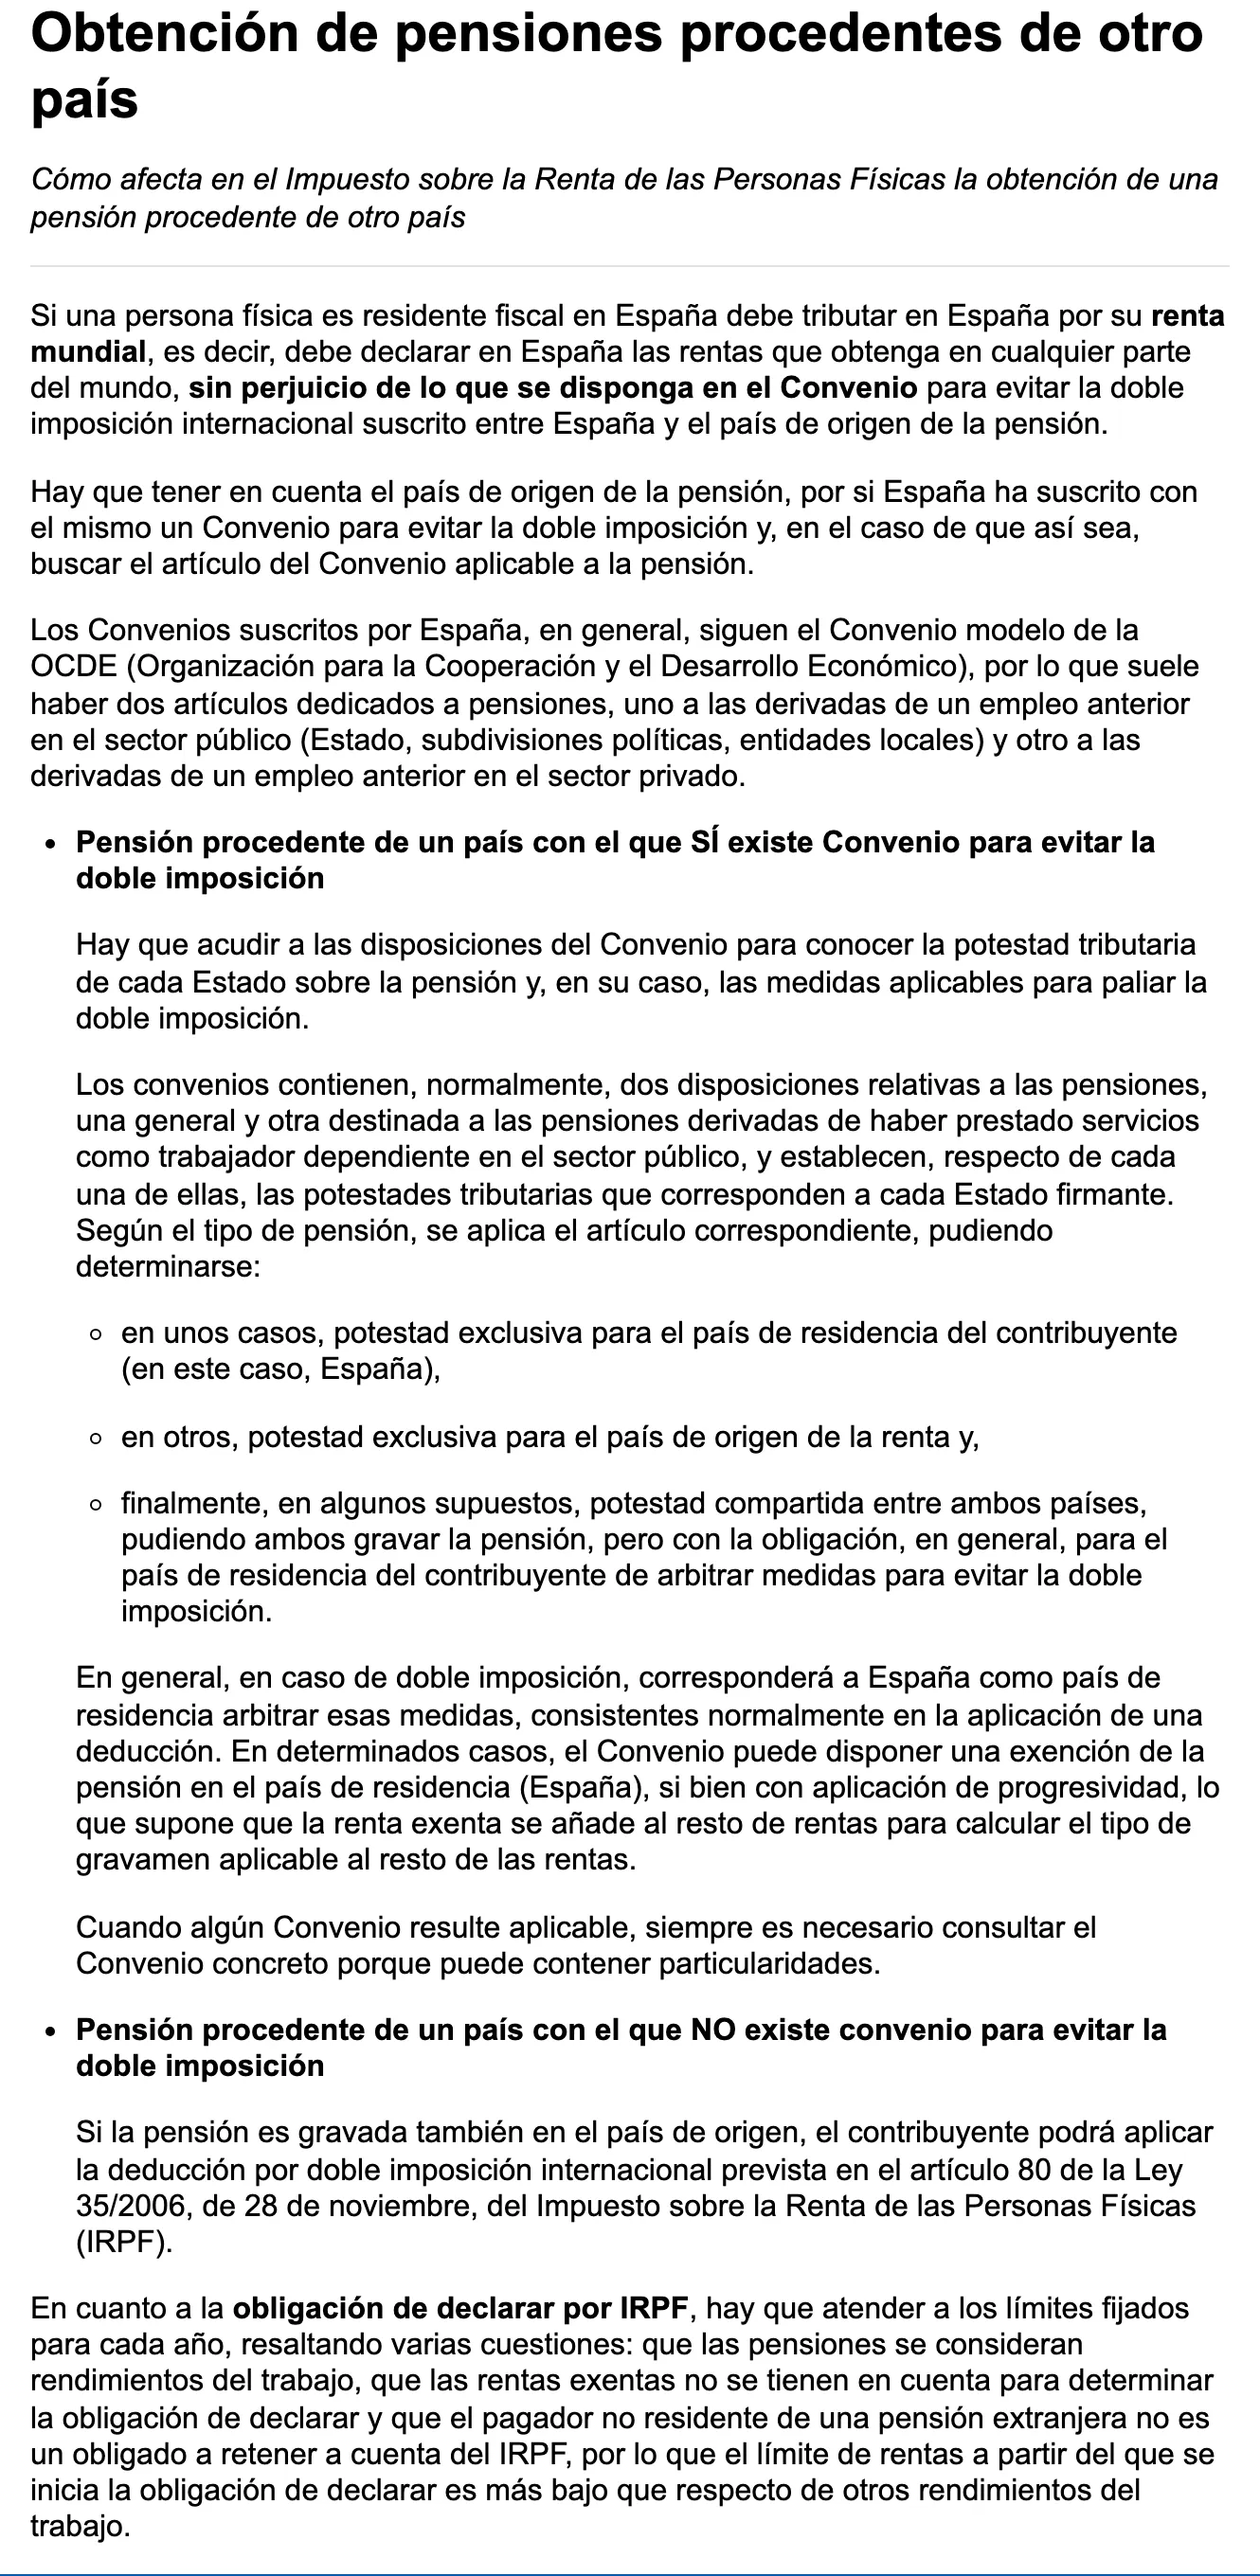
Yes for most German pensions, once you are tax resident; a civil-service pension is the exception. A tax resident of Spain is taxed on worldwide income, subject to any treaty with the country the pension comes from. Pensions count as employment income.
You are resident if you stay in Spanish territory more than 183 days in the calendar year. You are also resident if the main centre or base of your activities or economic interests is in Spain. The treaty applies to residents of one or both States.
What if you keep a home in Germany?
If you are resident of both States, the treaty treats you as resident only of the State where you have a permanent home. If you have one in both, it picks the State where your personal and economic ties are closest.
Which German pension do you have?
The payer decides the article. Pensions arising in one State and paid to a resident of the other may be taxed only in the State of residence, without prejudice to the government-service article.
- Paid by a State, a Land or a local authority for services to them: the government-service article.
- Paid under social-insurance legislation: the pensions article, with a German share when first paid from 31 December 2014.
- Paid for services in an economic activity of a State or public-law entity: the ordinary income articles.
- Any other pension arising in Germany, such as a company pension: taxed only in Spain, unless the incentivised-contribution rule below applies.
How is a social-insurance pension taxed?
Spain taxes it as the country of residence, and Germany may take a capped share. Read the cap before assuming a double bill.
Sin embargo, los pagos efectuados de acuerdo con la legislación sobre seguros sociales de un Estado contratante pueden someterse a imposición también en ese Estado en virtud de su normativa interna cuando el hecho que genere el derecho a percibir la renta se produzca a partir del 31 de diciembre de 2014.
However, payments made under the social-insurance legislation of a Contracting State may also be taxed in that State under its domestic law when the event giving rise to the right to receive the income occurs from 31 December 2014.
BOE · Convenio España-Alemania, art. 17.2
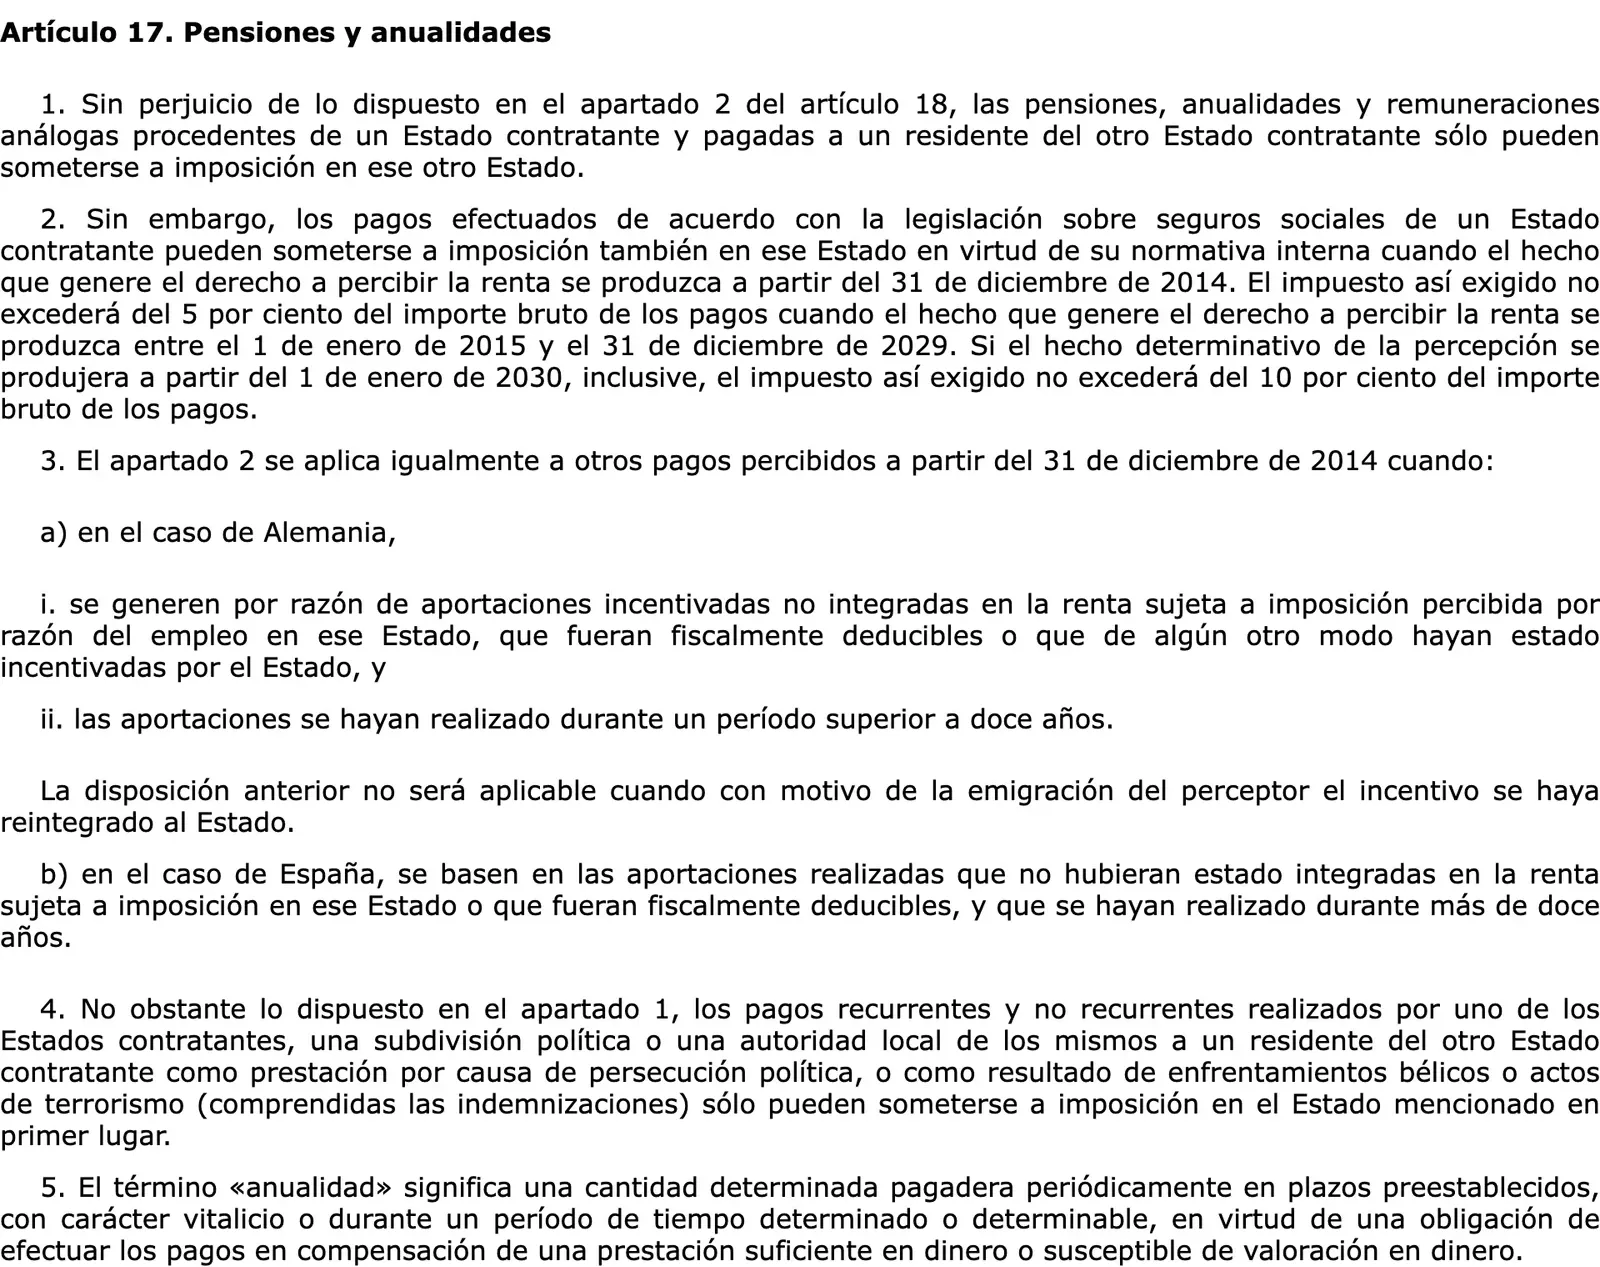
- The tax so charged may not exceed 5 per cent of the gross amount when the event falls between 1 January 2015 and 31 December 2029.
- If the event falls on or after 1 January 2030, the cap is 10 per cent.
- The event is the first date on which you receive the payment.
- If first paid before 31 December 2014, the German share does not apply, and only Spain taxes the pension.
Tip: the date of your first pension payment decides the cap, so note it before you file.
Some other payments received from 31 December 2014 follow the same rule. For Germany, these are payments from incentivised contributions, not included in taxable employment income, that were tax-deductible or state-incentivised and made over more than twelve years.
Spain relieves the double tax by deducting the tax paid in Germany from your Spanish income tax. The deduction may not exceed the part of the Spanish tax that corresponds to that income.
How is a Beamtenpension taxed?
Pensions paid by a State, its federal states or local authorities for services rendered to it may be taxed only in that State. The same goes for another public-law entity of that State.
sólo pueden someterse a imposición en ese Estado.
may be taxed only in that State.
BOE · Convenio España-Alemania, art. 18.2.a)
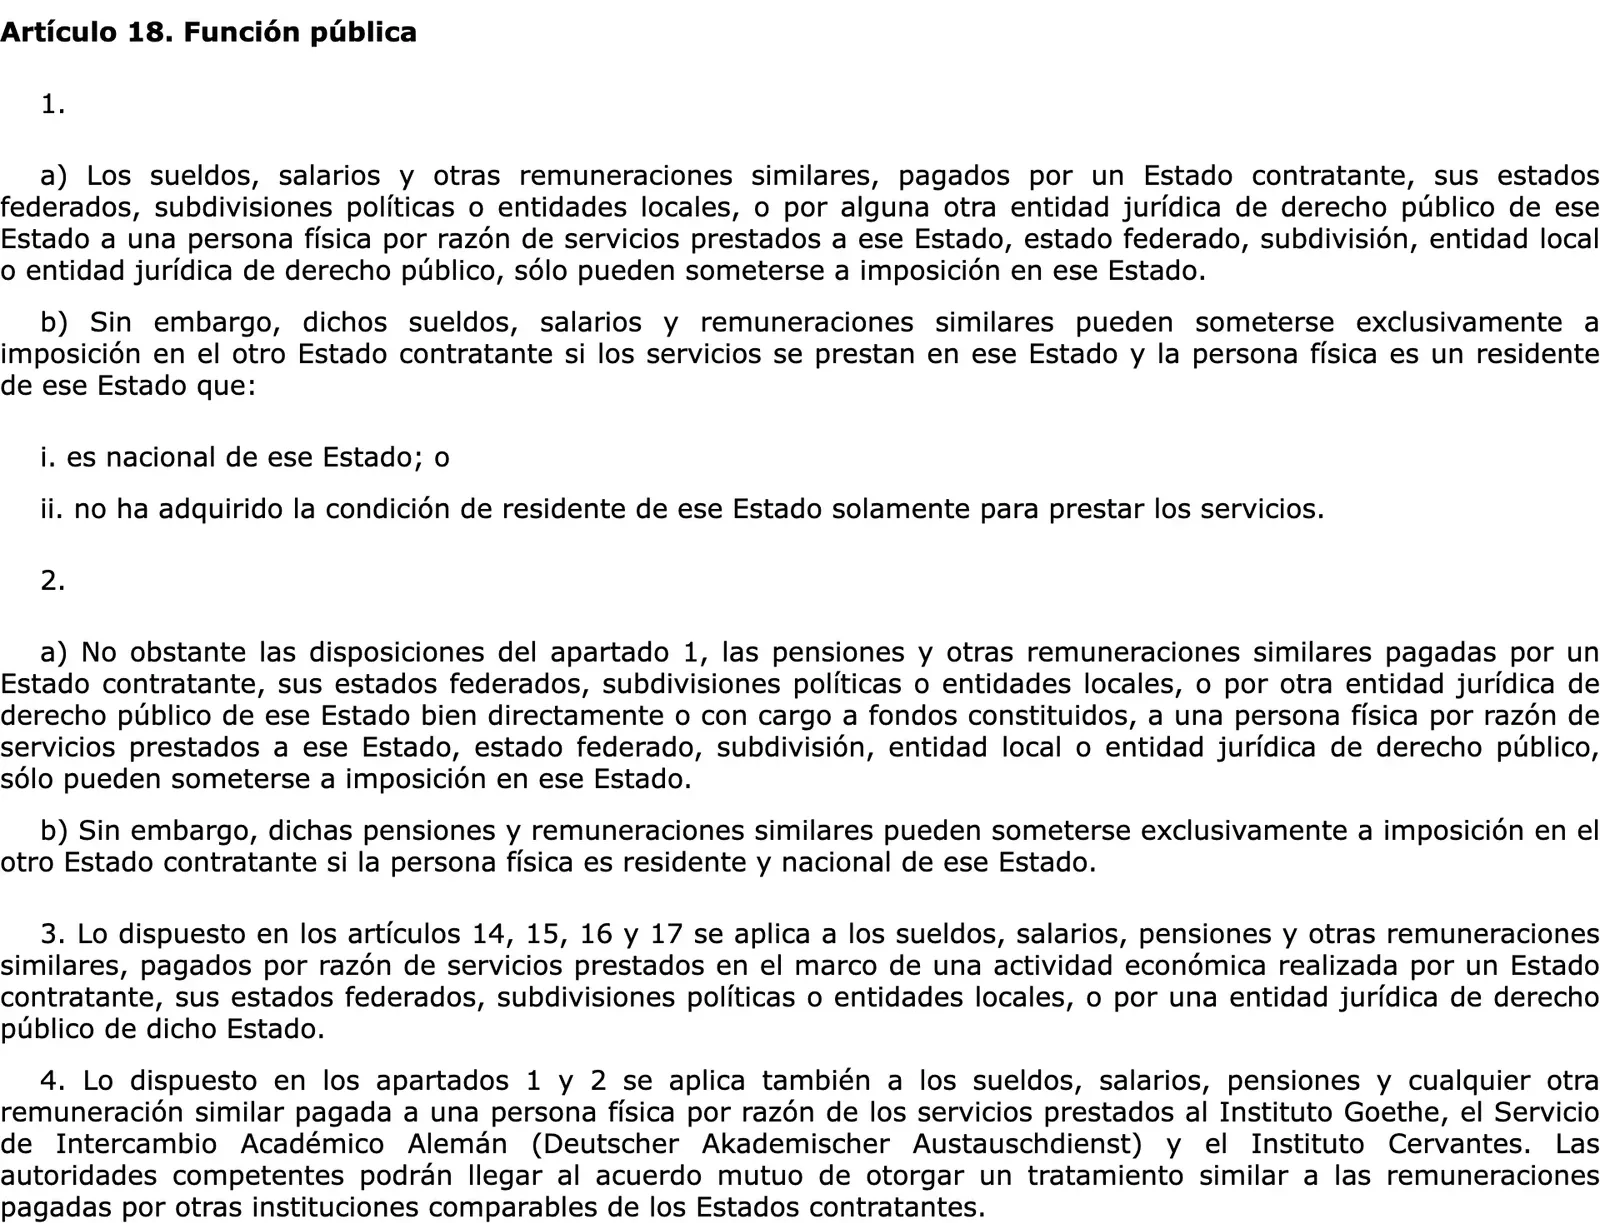
One exception: the pension may be taxed exclusively in the other State if the individual is a resident and a national of that State. So a German civil-service pension paid to a Spanish national living in Spain is taxed only in Spain. Pensions for services in an economic activity of the State fall under articles 14 to 17 instead.
Spain may take exempt income into account to calculate the tax on the rest of your income. The Tax Agency calls this progressivity: the exempt income is added to other income to set the rate on the rest. Exempt income is ignored when testing the duty to file.
What does it cost? A worked example
Take a social-insurance pension of 30000 euros a year, first paid between 2015 and 2029, as an example figure. The sums below apply the 2026 state and Valencian scales and the personal minimum, nothing else. A gestor runs your real figure.
Each scale gives the tax at the start of the band plus the rate on the part above it. The result is reduced by the tax the same scale gives on the personal minimum.
- State scale on 30000 euros: 3582.75 euros.
- Valencian scale on 30000 euros: 3394 euros.
- State scale on the personal minimum of €5,550: 527.25 euros.
- Valencian scale on the minimum of €6,105: 537.24 euros.
- Spanish IRPF after the minimum, as a total: 5912.26 euros.
- German tax at the 5 per cent cap, as an estimate: 1500 euros.
- Spanish IRPF after crediting German tax, as a total: 4412.26 euros.
The last two rows assume Germany takes the full 5 per cent and that you claim the deduction for it. The minimums rise by €1,150 (state) and €1,265 (Valencia) for taxpayers over 65.
A Beamtenpension has no Spanish tax line, because only the paying State may tax it. Spain may still count it when setting the rate on your other income.
What do you file in Spain?
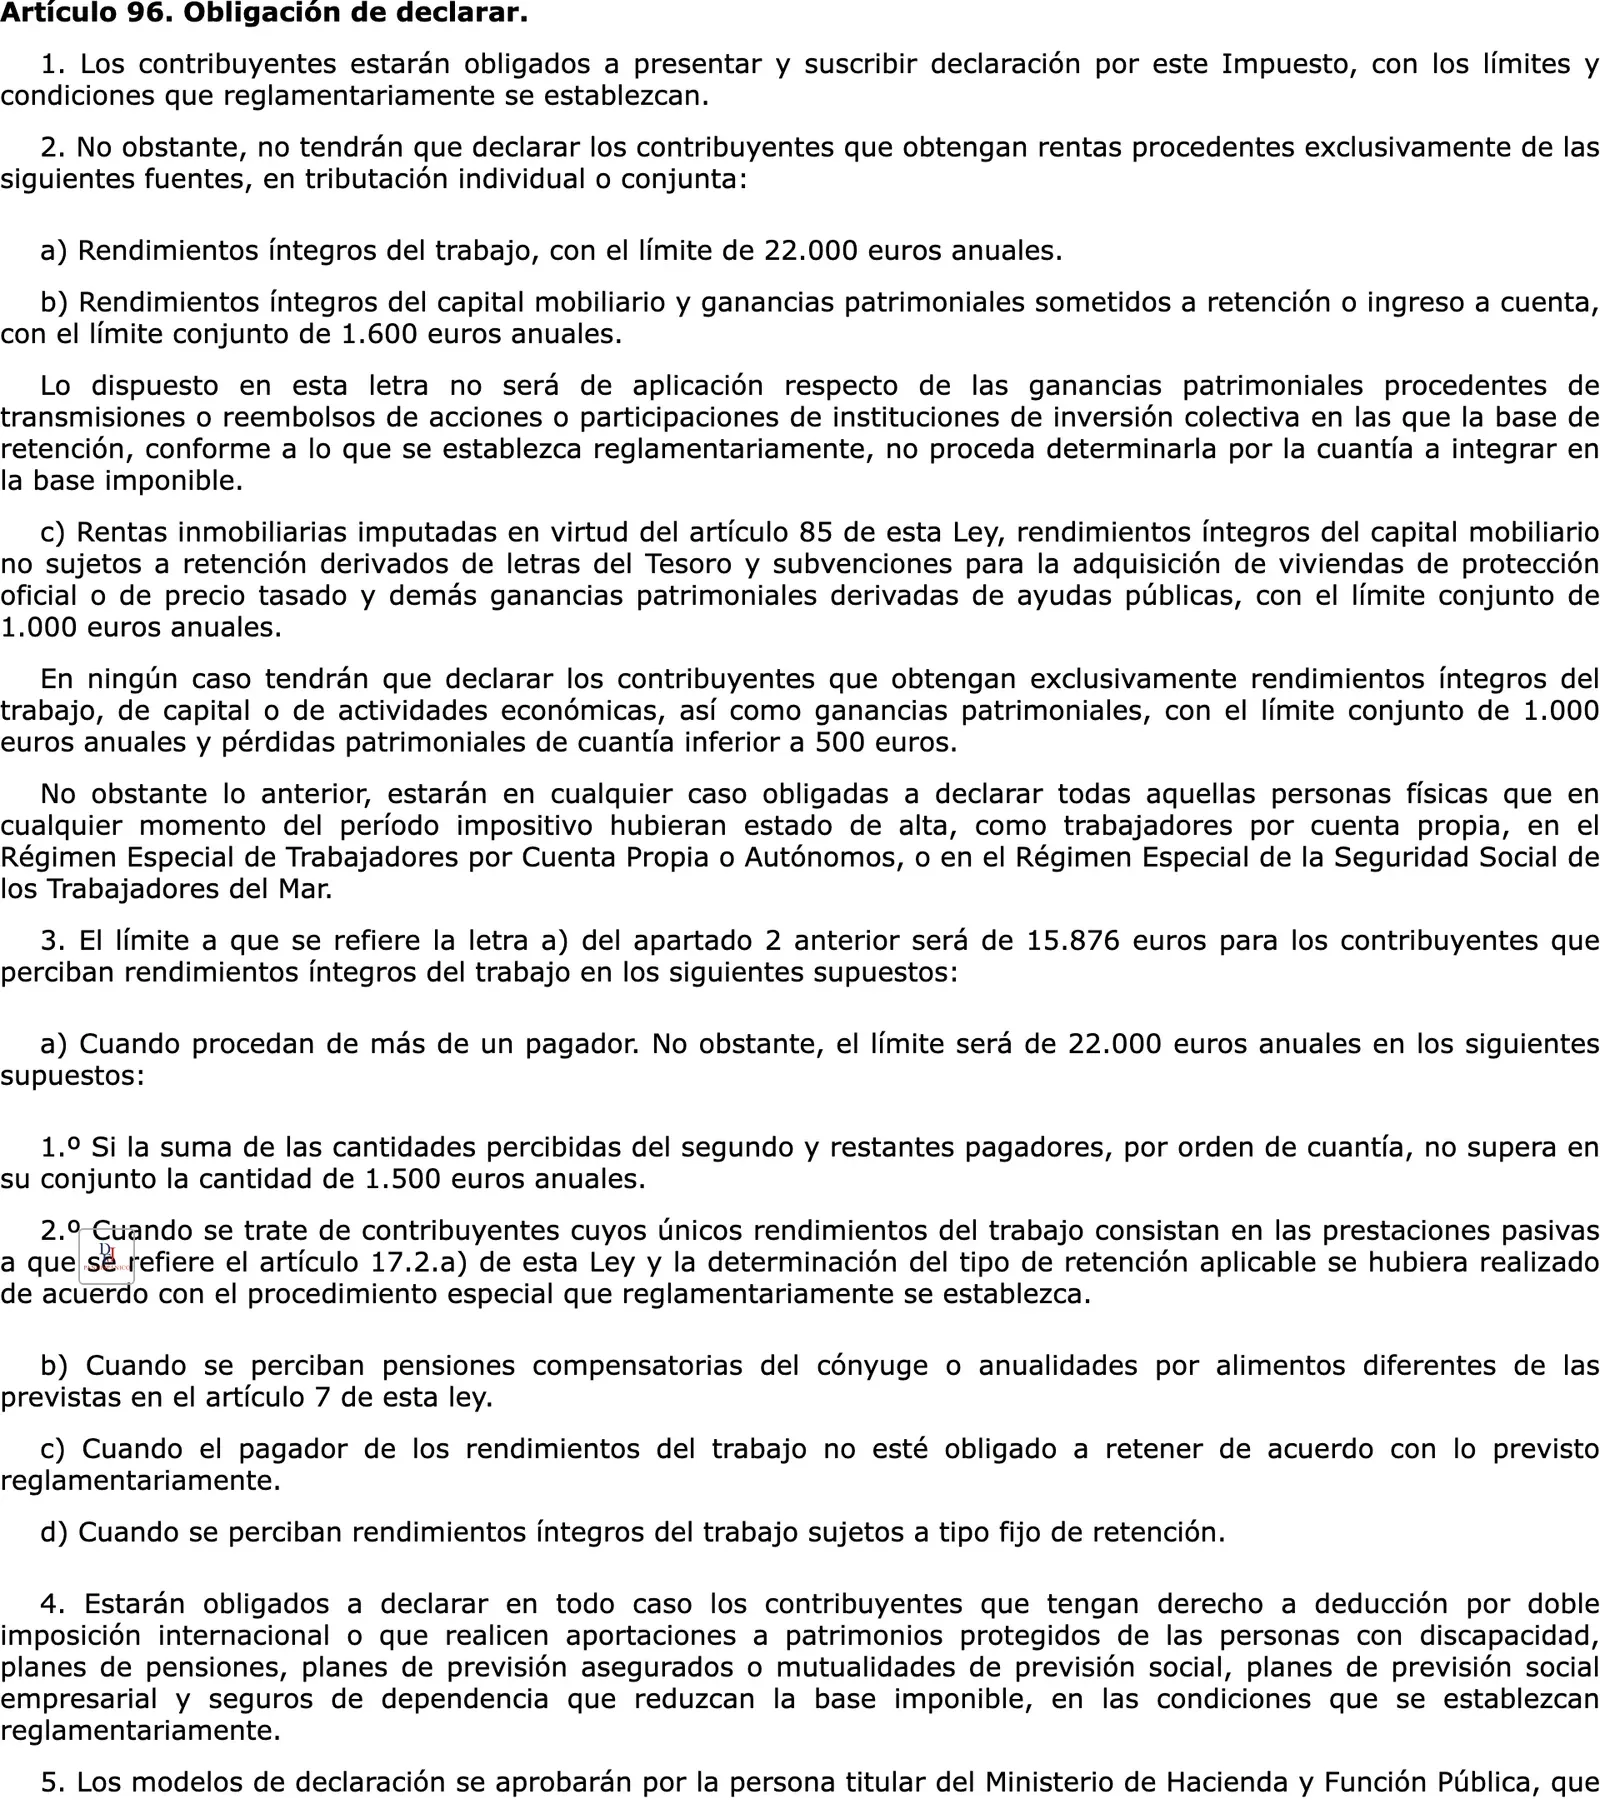
With a German pension, expect to file. The general no-return limit for employment income, pensions included, is €22,000 a year. It drops to €15,876 when the payer is not obliged to withhold, and a non-resident payer of a foreign pension is not.
You file in any case if you are entitled to the international double taxation deduction, which you are when Germany taxes your pension. Spain normally relieves double taxation with a deduction. For the 2025 tax year the return ran from 8 April to 30 June 2026.
For treaty relief at source, the source State asks for a certificate of residence from the competent authority of the other State. For treaty countries, the Spanish tax authorities certify that you are resident within the meaning of the treaty. It is issued in Spanish and English.
Assets abroad have their own test. There is no duty to report foreign accounts when the combined 31 December balances and the combined average balances each stay within €50,000. The foreign-assets guide has the rest.
Does the Beckham regime change this?
Yes, if you opted for it. Articles 4 and 6 to 21 do not apply to Spanish taxpayers who opted for the non-resident tax regime of article 93 of the IRPF law. The Beckham law guide has the conditions.
What comes next?
The general rules are in the pension tax guide and the tax residency guide. Health cover is the next question: read the S1 guide for EU pensioners. The multilateral convention of 24 November 2016 may have affected this treaty.
Photo credits
- The Turia gardens, the long park along the old river bed in Valencia: Dorieo, Wikimedia Commons (opens in a new tab) (CC BY-SA 4.0)
- Plaza del Ayuntamiento, in the centre of Valencia: Julián Monrabal, Wikimedia Commons (opens in a new tab) (CC0)
- The Torres de Quart, one of the old city gates of Valencia: Wikimedia Commons (opens in a new tab), Diego Delso (CC BY-SA 3.0)
Step by step
- Check your Spanish tax residenceMore than 183 days in the calendar year, or your main base of economic interests in Spain.
- Find your pension's articleA public-service pension follows the government-service article. A social-insurance payment follows the pensions article, with a German share only if first paid from 31 December 2014. Other pensions arising in Germany are taxed only in Spain.
- Apply the Spanish scales and the German creditState and Valencian scales, reduced by the tax on the personal minimum. Spain deducts German tax paid.
- Test the duty to fileWith a foreign pension payer the limit is €15,876; the deduction for double taxation always means a return.
Not confirmed: Whether your pension is a social-insurance payment, a company pension or a Riester or Rürup pension: a gestor classifies it before you file. How Germany charges its capped share and which German forms apply: ask the Deutsche Rentenversicherung or a German tax adviser.
Reach readers planning life in Valencia. Advertise → hello@settlevalencia.com
Common questions
Do I pay Spanish tax on my German state pension?
If you are a tax resident, yes: Spain taxes worldwide income, subject to the treaty. Pensions arising in Germany and paid to a resident of Spain may be taxed only in Spain, without prejudice to the government-service article. Payments under social-insurance legislation may also be taxed in Germany when first paid from 31 December 2014.
Is a Beamtenpension taxed in Spain?
Not usually. Pensions paid by a State, its federal states or local authorities for services to them may be taxed only in that State. The exception is a Spanish national resident in Spain: then only Spain taxes it. Spain may still count the exempt amount when it sets the rate on your other income.
Can Germany still tax my pension after I move?
For social-insurance payments first paid from 31 December 2014, yes, up to a cap. The cap is 5 per cent of the gross amount when the event giving rise to the right falls between 1 January 2015 and 31 December 2029. From 1 January 2030 the cap is 10 per cent. Spain deducts the tax paid in Germany.
Do I have to file a Spanish tax return?
Usually yes. A foreign pension payer is not obliged to withhold, so your limit is €15,876, not €22,000. You must file in any case if you are entitled to the international double taxation deduction, as you are when Germany taxes your pension.
How much Spanish tax would a sample pension pay?
As an example only, 5912.26 euros on the 2026 state and Valencian scales after the personal minimum. Taking the 5 per cent German cap as 1500 euros and crediting it leaves 4412.26 euros. Other deductions are not applied.
Does Germany or Spain issue the residence certificate?
Spain does. For countries with a treaty, the Spanish tax authorities certify that you are resident within the meaning of the treaty, in Spanish and English. The source State requests a certificate from the other State's competent authority.
Is the Germany-Spain treaty still the current one?
The convention signed in Madrid on 3 February 2011 is the one on the Spanish treaty list. The multilateral convention of 24 November 2016 may have affected its provisions. The pension articles are quoted above from the BOE consolidated text.
Read next
General information checked against the sources listed above, not legal advice for your situation. Rules and office practice change; confirm with the immigration office or a licensed adviser before you act. See how guides are checked.
Spotted an error? Report it.