Spain Tax Return Deadline: Key IRPF Dates for Residents
The Renta 2025 window closed on 30 June 2026. If you split the payment, the 40% second part is due by 5 November 2026. Orden HAC/277/2026 set these dates for tax year 2025. A late return filed without a prior requirement carries a surcharge of 1% plus 1% for each full month of delay.
Also in: Deutsch
On this page
- Is the Renta window still open?
- Do you have to file a return?
- How do you pay, or get a refund from abroad?
- What is still due this autumn?
- Autónomo? Quarterly dates for the instalment and VAT
- Foreign assets: when are they reported?
- Non-resident with Spanish property?
- What happens if you file late?
- Arriving in Spain in 2026?
- Key dates at a glance
- Step by step
- Common questions
Landed in Spain and wondering when the tax return is due? The Renta 2025 window has closed, and the dates still ahead are below.
Is the Renta window still open?
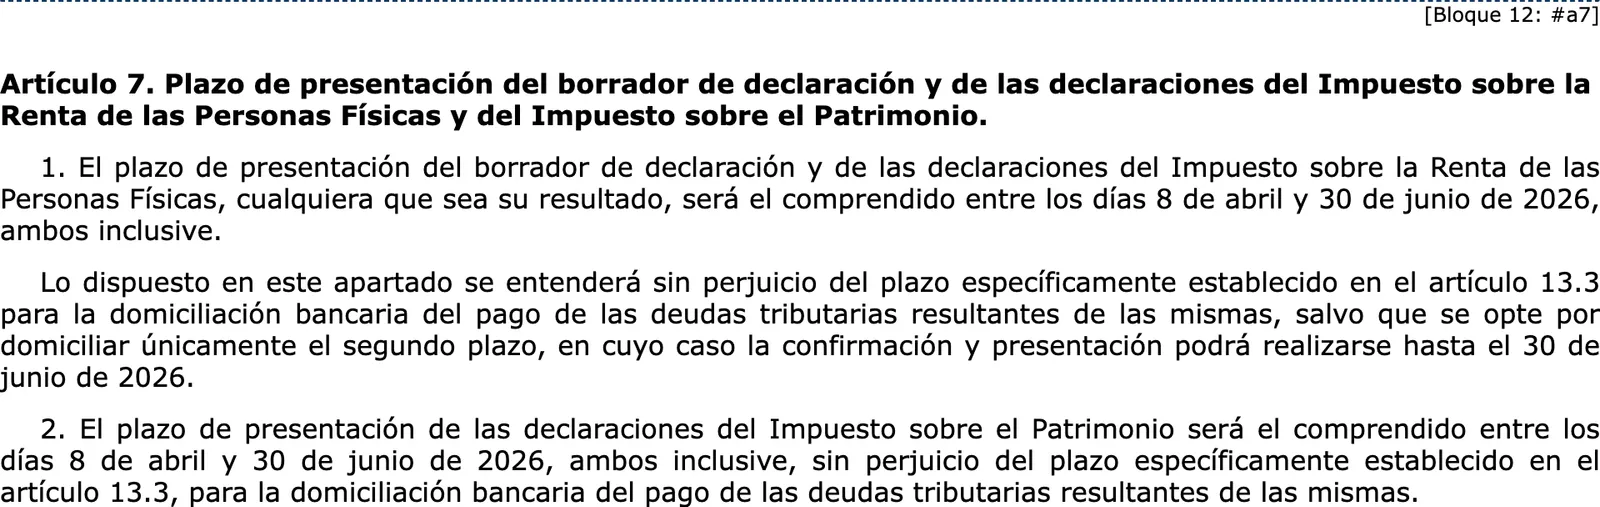
No. The 2025 return was due between 8 April and 30 June 2026, both included, whatever the result. Direct debit ended on 25 June 2026.
cualquiera que sea su resultado, será el comprendido entre los días 8 de abril y 30 de junio de 2026, ambos inclusive.
whatever their result, will run from 8 April to 30 June 2026, both included.
BOE · Orden HAC/277/2026, art. 7.1
Orden HAC/277/2026 approves the forms and sets the periods for tax year 2025. The Tax Agency calendar gives the same dates for online filing. Look for the order covering tax year 2026 when it appears.
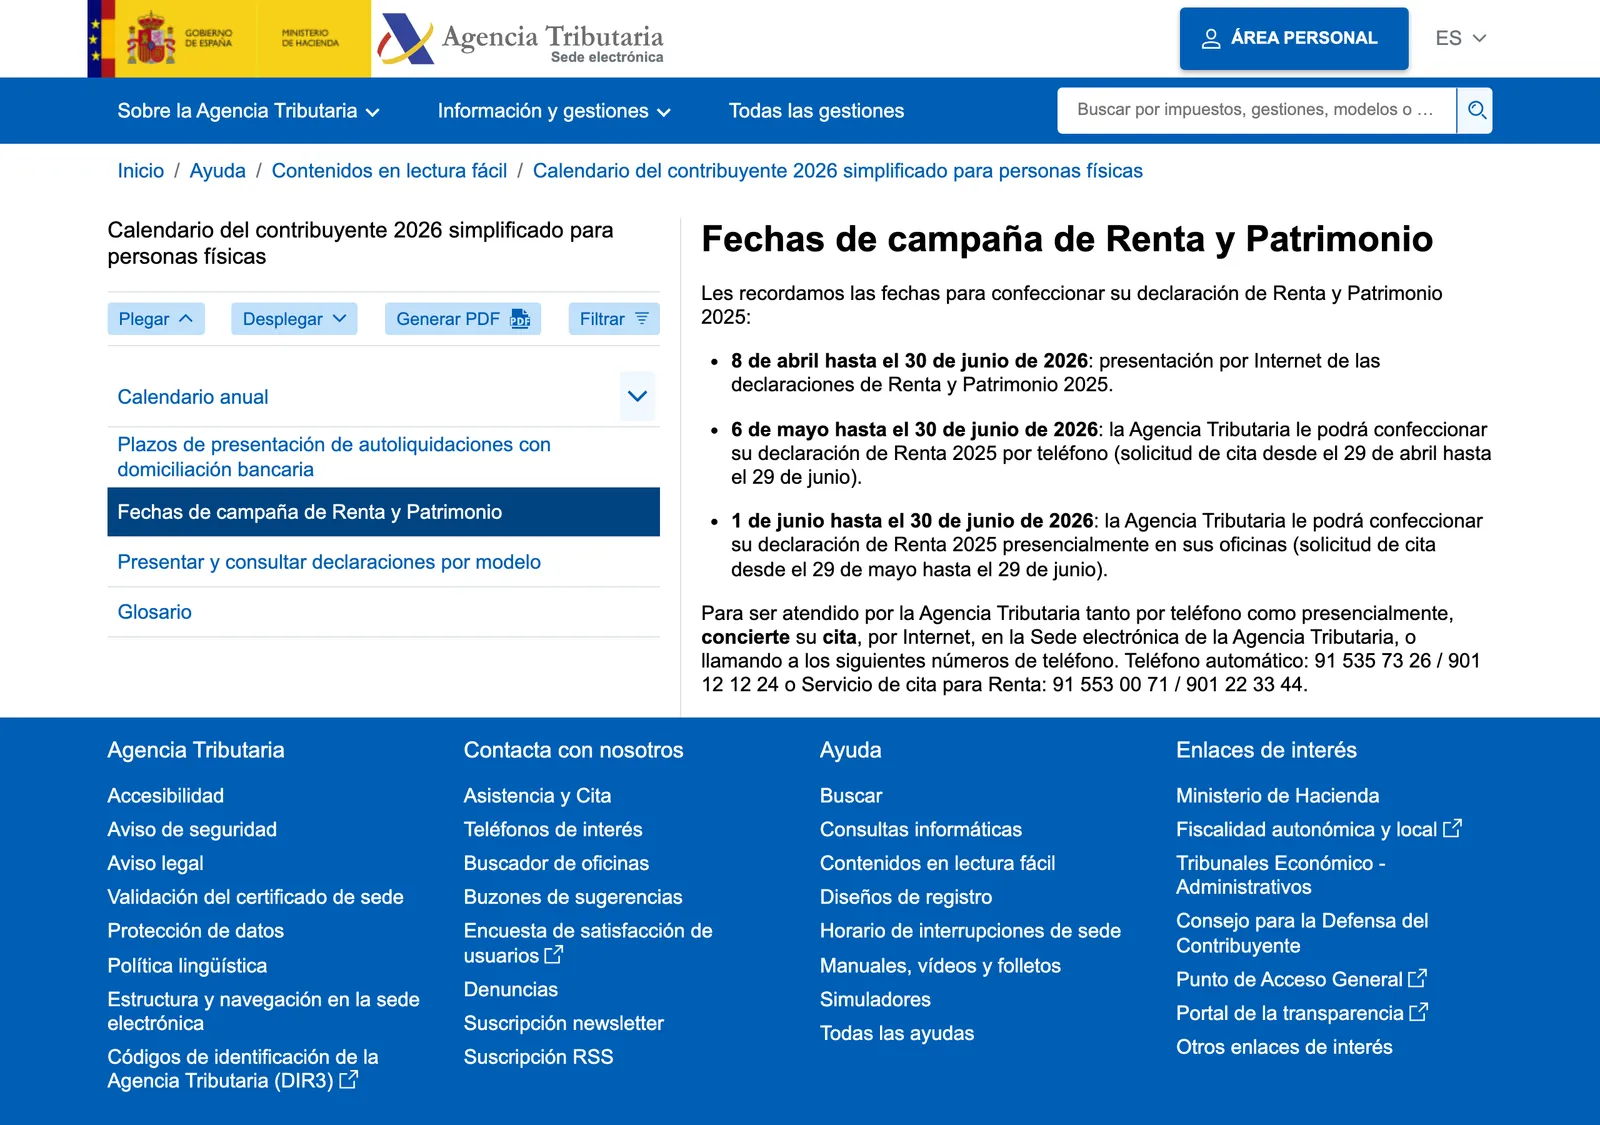
In 2026 the Tax Agency also prepared returns by phone and in person, by appointment. The Valencia delegation is on the map.
Placa de l'Ajuntament 9, 46002 Valencia, Spain · Open in Google Maps (opens in a new tab)
Do you have to file a return?
The Renta is the IRPF return of Spanish tax residents, who are taxed on their whole income. A non-resident with Spanish property files Modelo 210 instead, covered below.
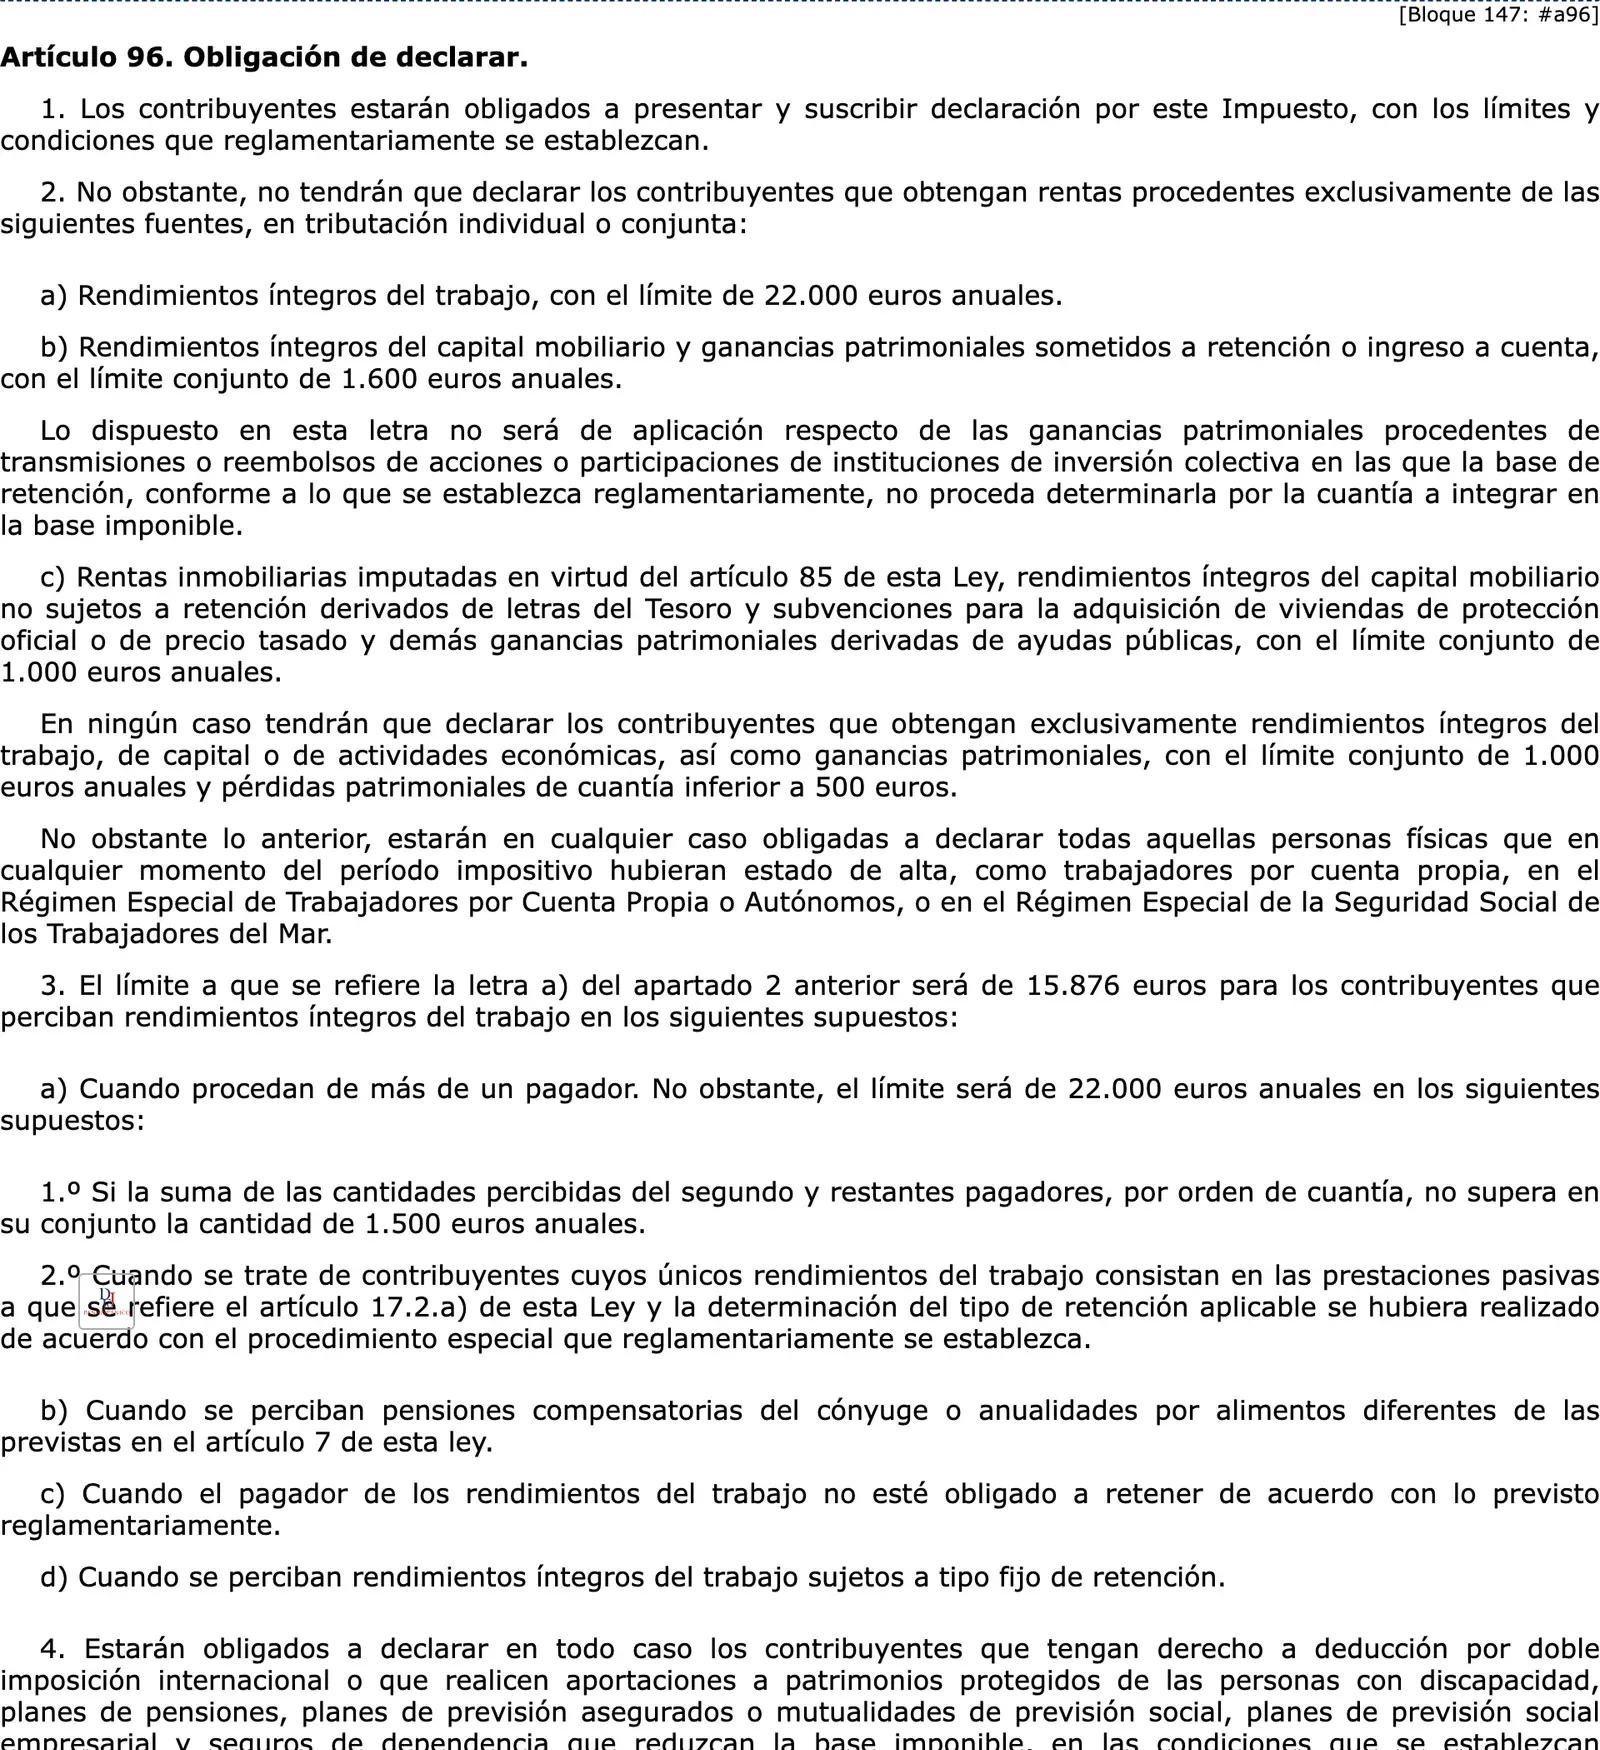
Check the limits first. Under the IRPF law (Ley 35/2006), when all your income comes from these sources, no return is required up to these gross amounts, and the limits count jointly where shown.
| Income source | No return up to |
|---|---|
| Employment income, one payer | €22,000 a year |
| Employment income, more than one payer | €15,876 a year |
| Same, if second and later payers paid €1,500 or less | €22,000 a year |
| Payer not obliged to withhold, such as a foreign pension payer | €15,876 a year |
| Movable-capital income and gains subject to withholding | €1,600 a year, jointly |
| Imputed property income and minor items | €1,000 a year, jointly |
You file whatever your income in two cases.
- You were registered as self-employed (RETA) at any time in the tax year.
- You are entitled to the international double taxation deduction, or you contributed to pension plans and similar schemes that reduce the tax base.
The guide to Spanish tax residency explains who counts as resident.
How do you pay, or get a refund from abroad?
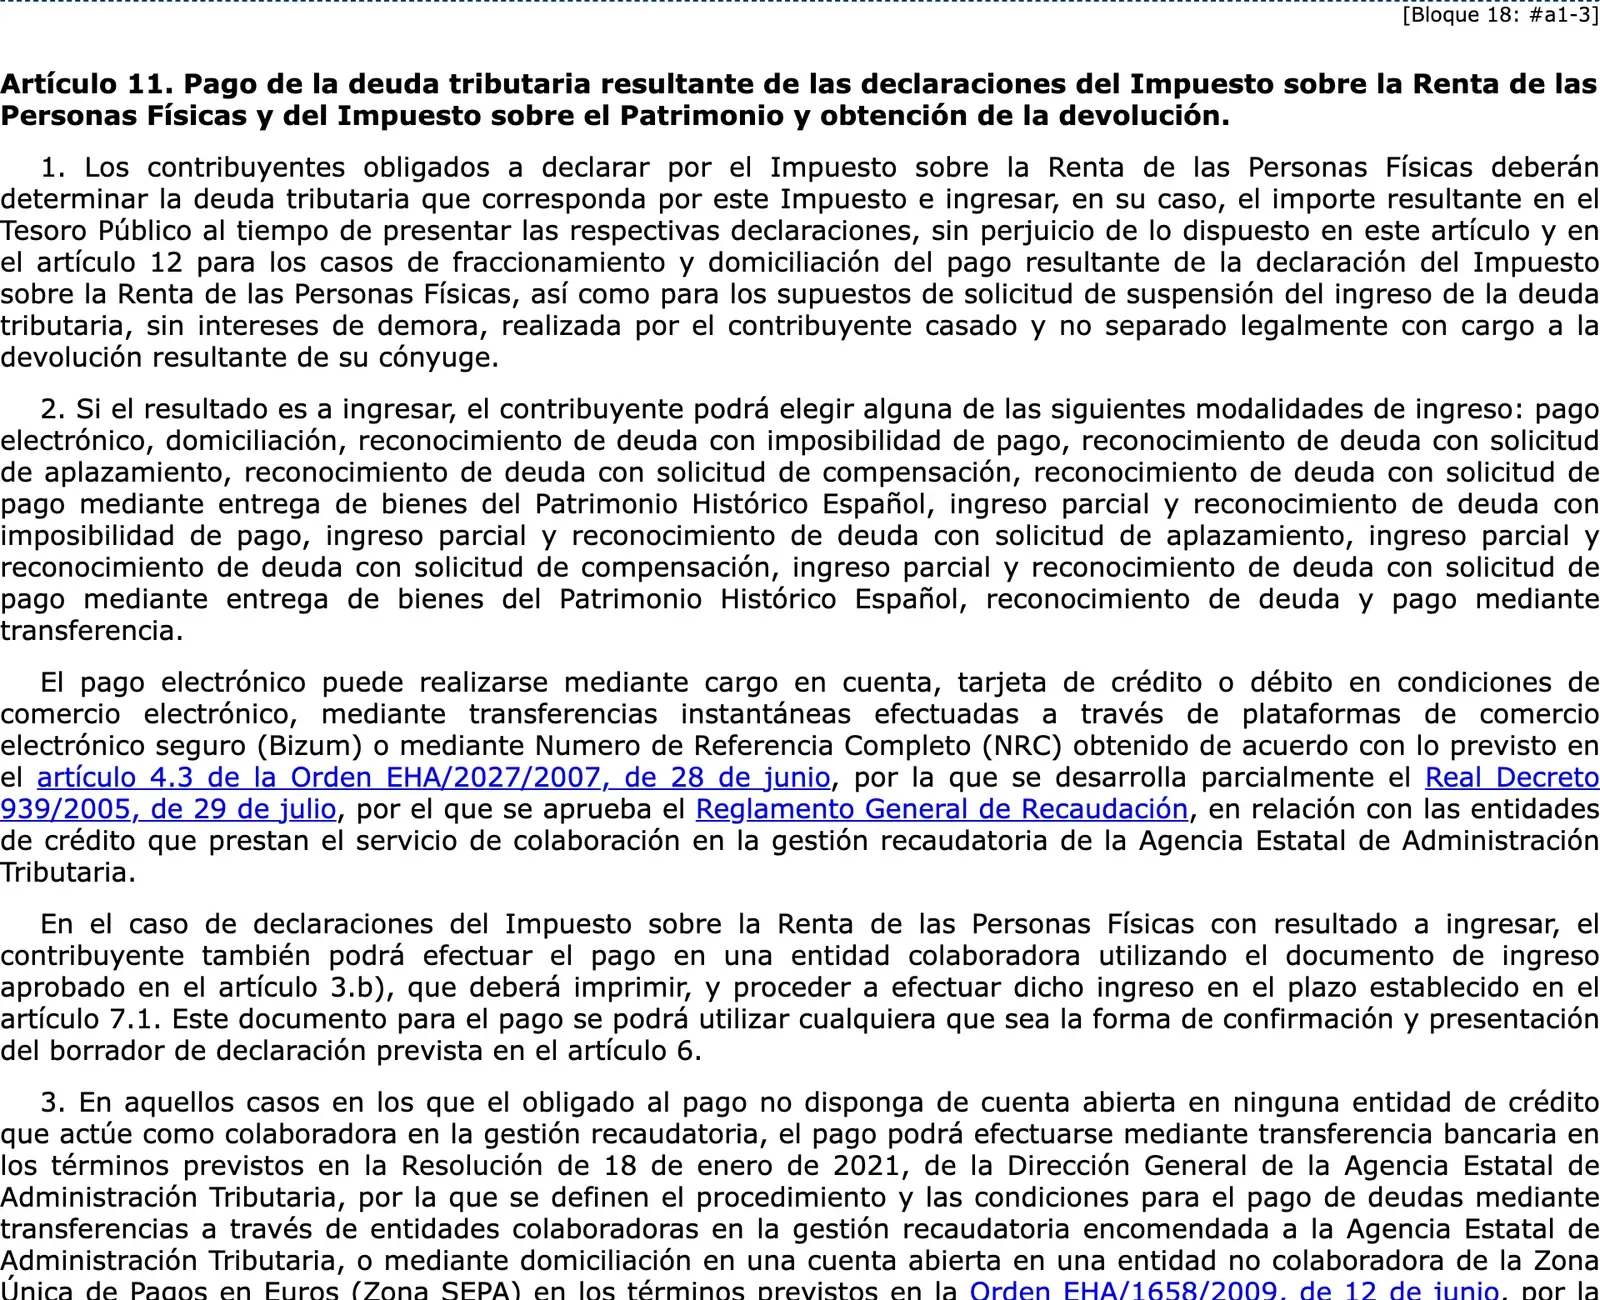
Pay online by direct charge to an account, by card, by Bizum, or with a complete reference number (NRC). Direct debit needs an account in your name at a collaborating bank in Spanish territory.
With no such account, direct debit from a bank in the SEPA zone is possible. With no account at a collaborating bank, you may pay by bank transfer.
If you are owed money, you may ask for a transfer, waive the refund, or ask for the transfer through a financial institution established abroad.
File online with a recognised electronic certificate, Cl@ve Móvil or a reference number. Keep the proof of filing: it carries a 16-character verification code with the date and time.
What is still due this autumn?
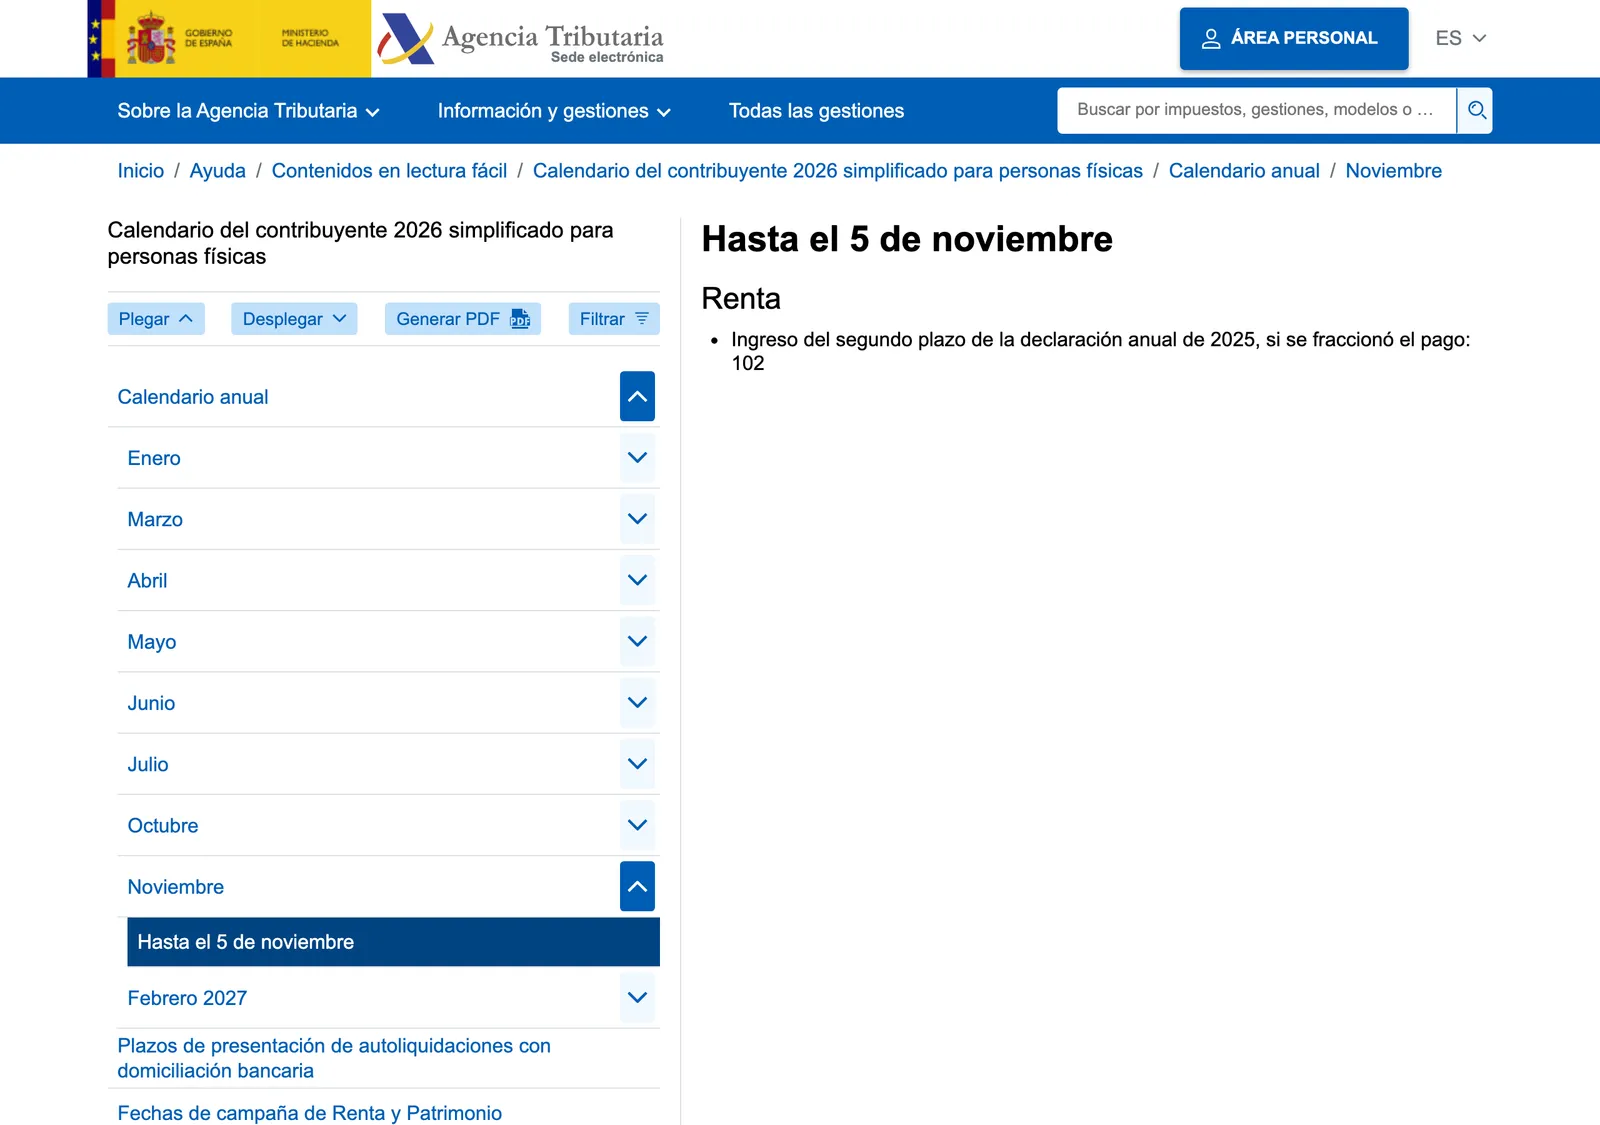
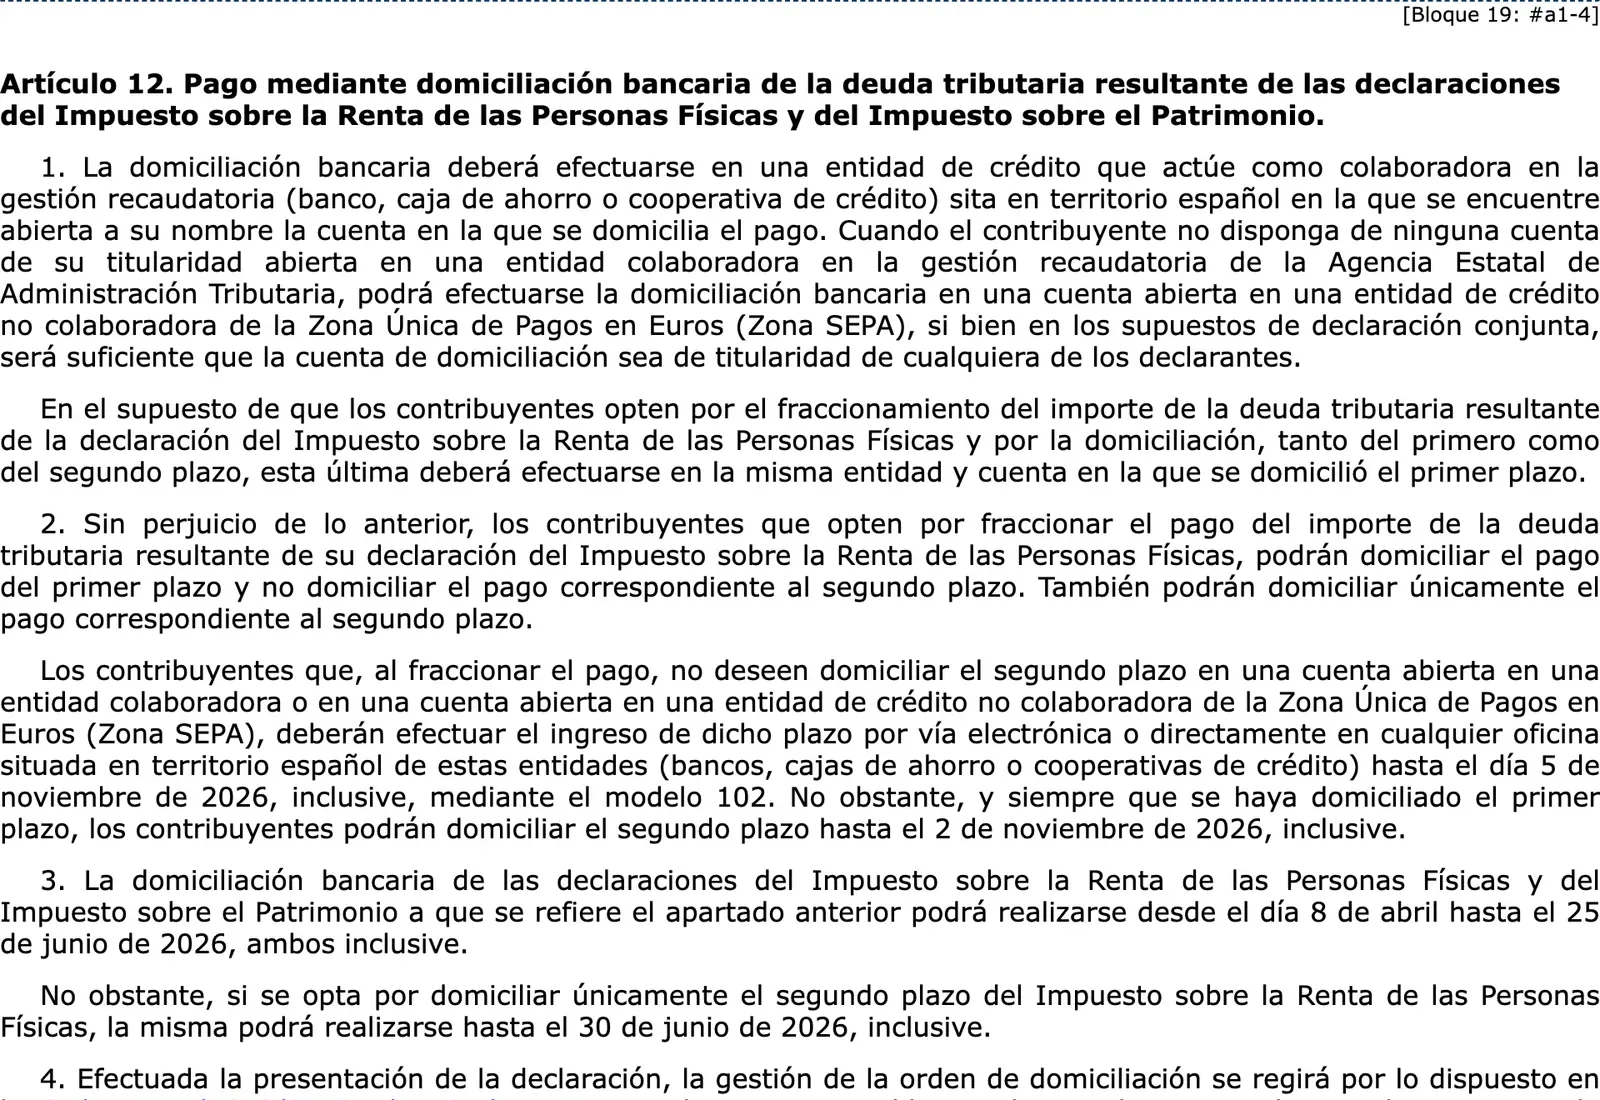
If you split the 2025 payment, the second part is 40% of the debt, due by 5 November 2026, inclusive. The split needs a return filed inside the ordinary period.
If the second part is not debited, pay it with Modelo 102, electronically or at a bank office in Spain, by 5 November 2026. If you debited the first part, you may debit the second up to 2 November 2026.
The same 5 November payment is on the Tax Agency calendar. Paying with Modelo 102 by that date is the route with no open question.
Autónomo? Quarterly dates for the instalment and VAT
The quarterly IRPF instalment is an obligation of businesspeople and professionals, not of every taxpayer. Modelo 130 is the form for that IRPF instalment in direct estimation. Modelo 303, the VAT return, is on the Tax Agency calendar for the third and fourth quarters of 2026.
| Quarter | Window |
|---|---|
| First three quarters of the year | Modelo 130: 1st to 20th of April, July and October |
| Third quarter of 2026 | Modelo 303: up to 20 October 2026 |
| Fourth quarter | Modelo 130: 1 to 30 January, per the regulation, with no entry on the Tax Agency calendar yet; Modelo 303 for 2026: up to 1 February 2027 |
Nothing to pay in a quarter? File a nil return. Professionals skip the instalment when at least 70% of last year’s activity income was withheld.
When the last day falls on a non-working day, the period ends on the next working day. The autónomo registration guide covers the rest.
Foreign assets: when are they reported?
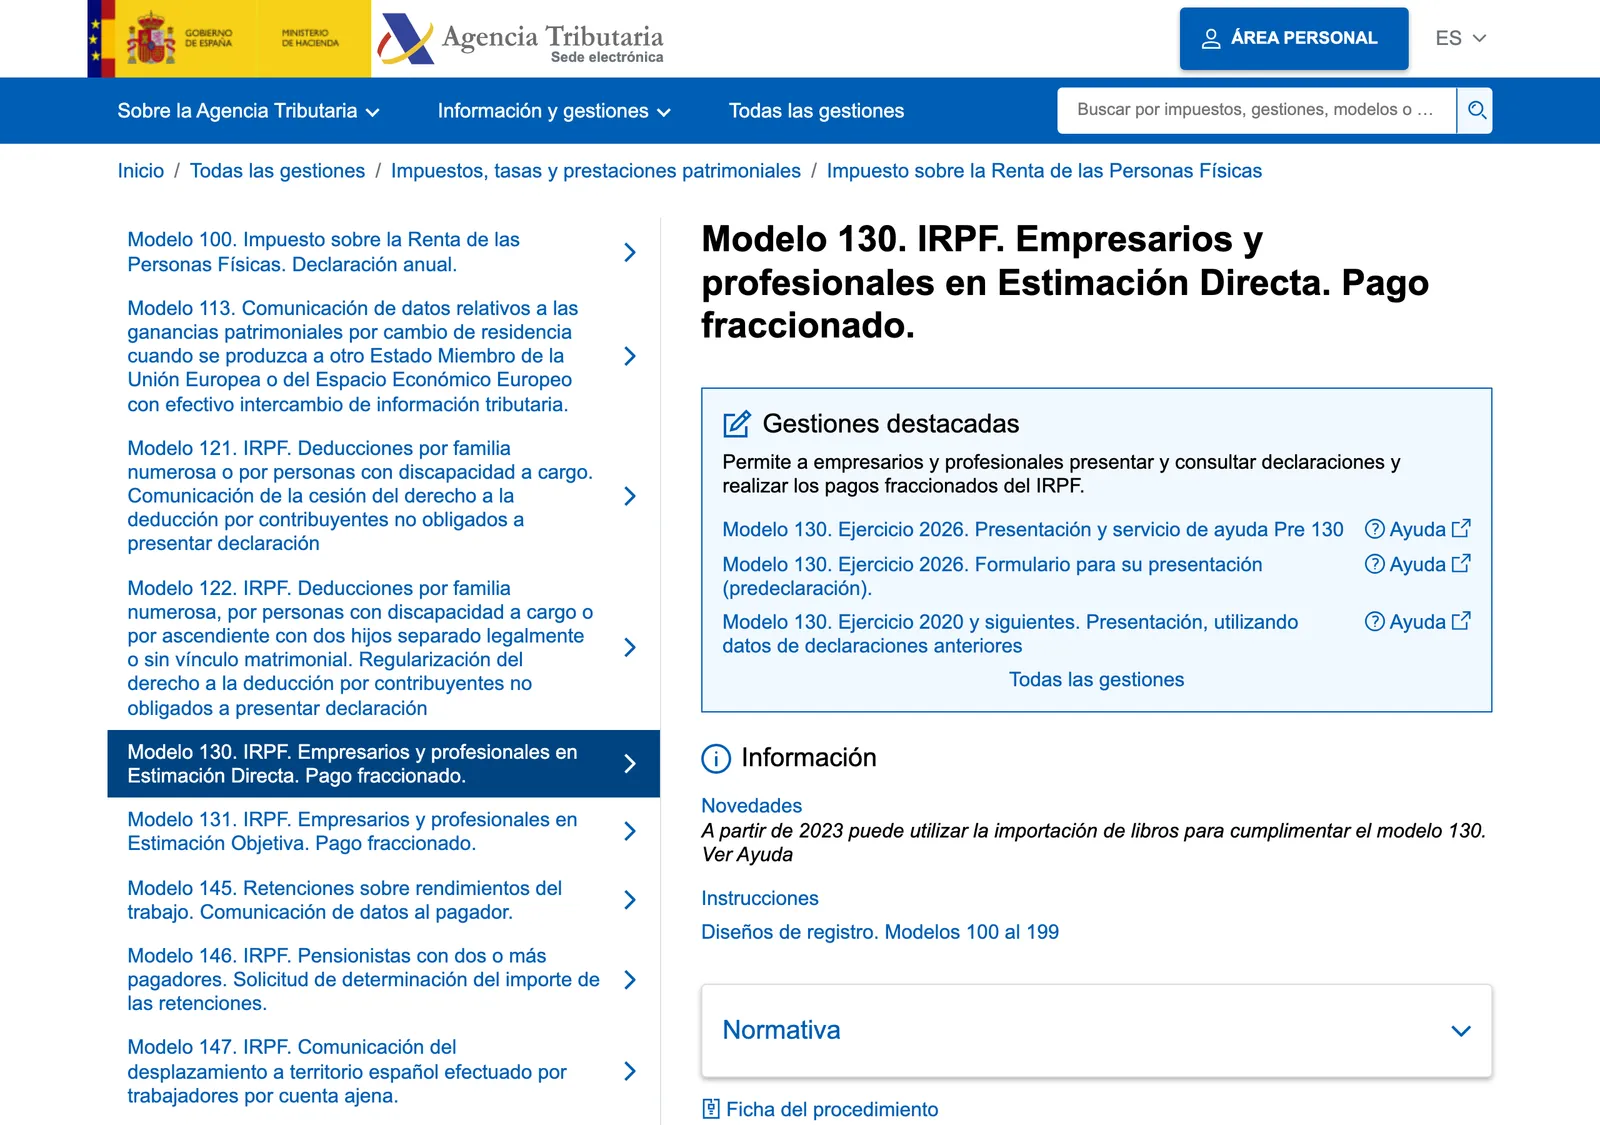
Under Orden HAP/72/2013, Modelo 720 is filed between 1 January and 31 March of the year after the one reported. The 2026 window, for the year before, ran from 1 January to 31 March 2026. This year’s assets go in the same window next year.
Modelo 721, for virtual currencies held abroad, uses the same dates under Orden HFP/886/2023. Residents taxed on their whole income are among those who file Modelo 720. Filing depends on value thresholds, set out with the penalties in the guide to the foreign assets return.
If the website fails for technical reasons, Modelo 720 may still go in during the four calendar days after the deadline.
Non-resident with Spanish property?
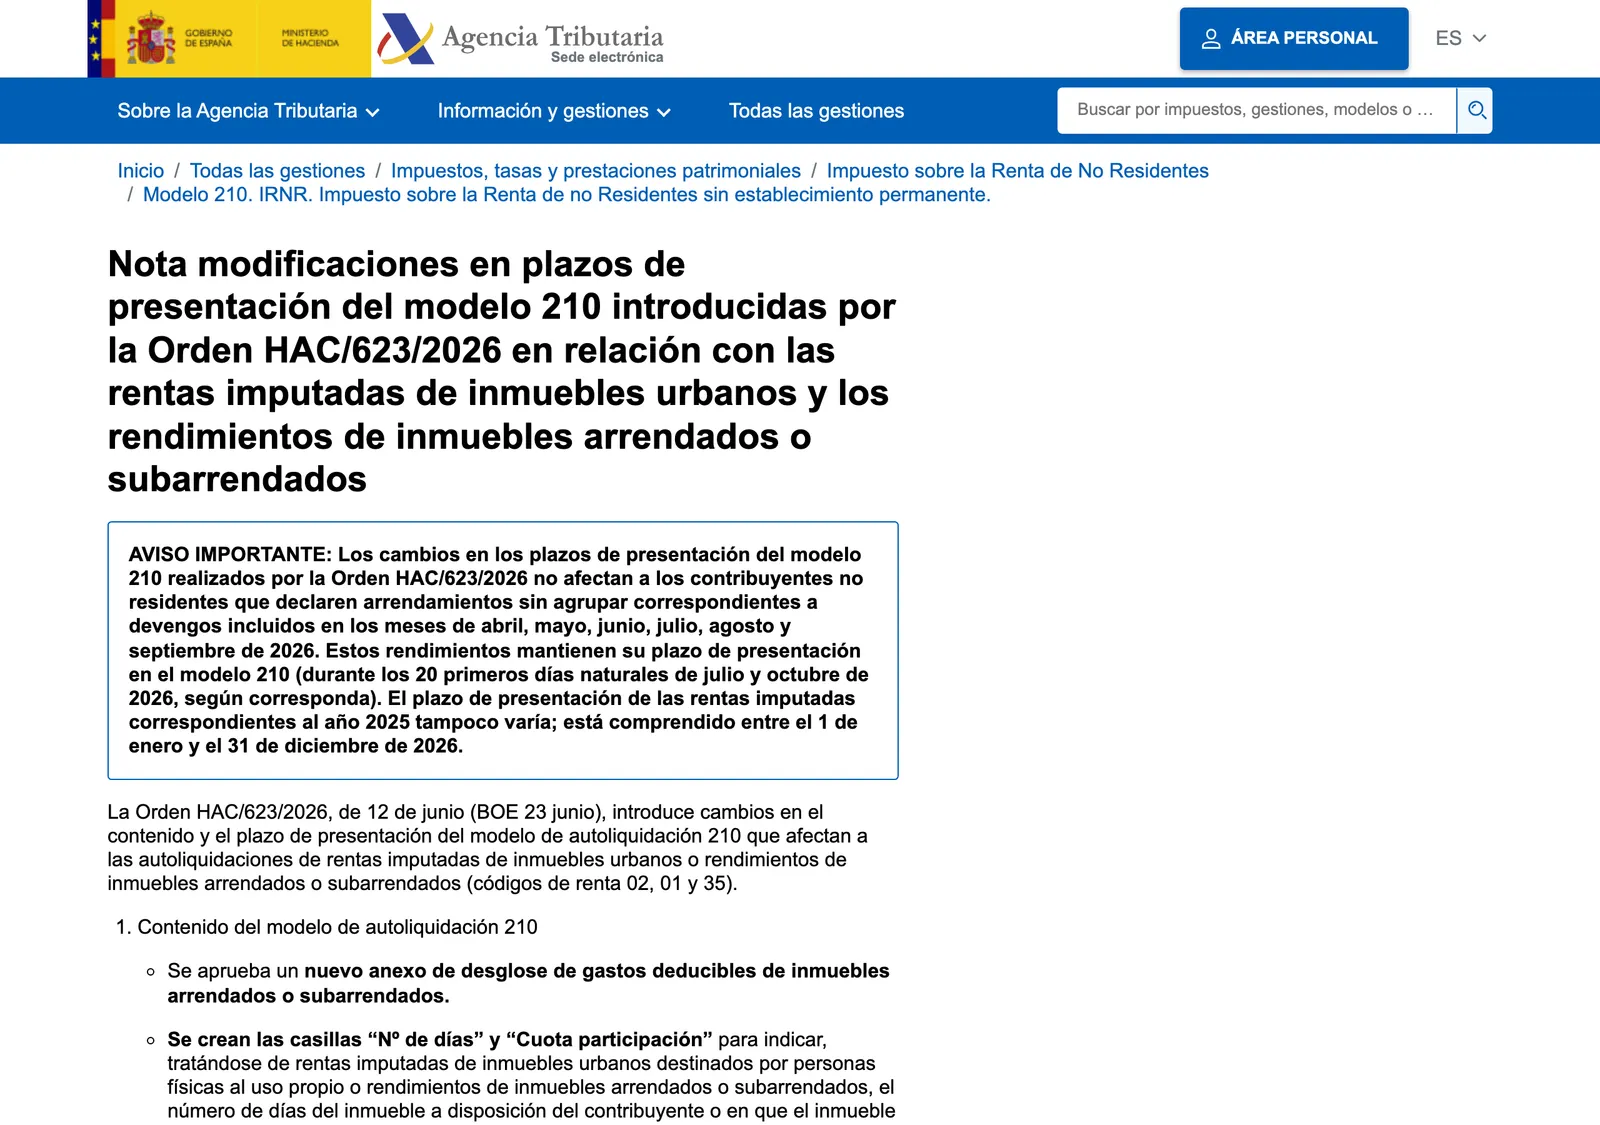
Orden HAC/623/2026 changed the content and filing periods of Modelo 210 for imputed income and rent.
| Income | Filing window |
|---|---|
| Imputed property income of 2025 | 1 January to 31 December 2026 |
| Imputed property income of 2026 | 1 April to 31 December of the year after accrual, starting 1 April 2027 |
| Rent of July to September 2026, declared separately | First 20 calendar days of October 2026 |
| Rent of October to December 2026, declared separately | 1 to 20 April 2027 |
| All rent of 2026, declared as a group | 1 to 20 April 2027 |
Under the new rule, rent is filed in the first twenty calendar days of April of the year after accrual, separately or grouped. Since accruals from 2024, the grouping period is annual, not quarterly.
What happens if you file late?
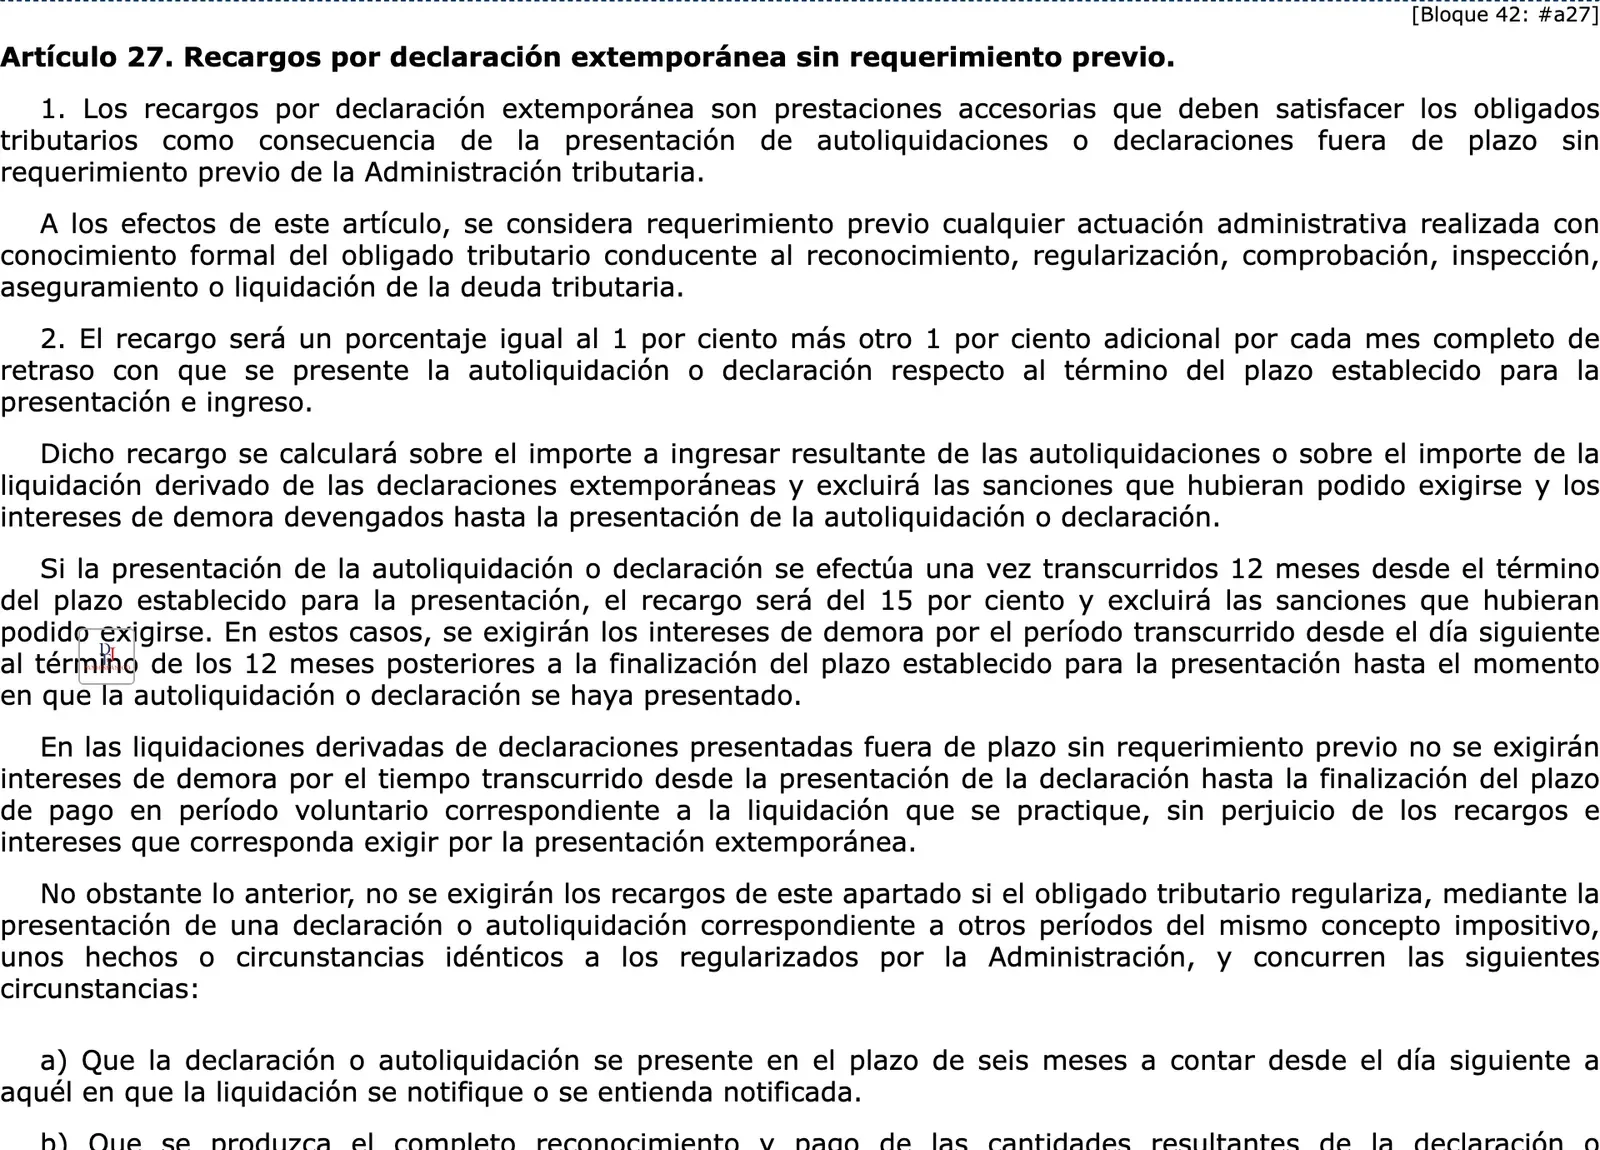
The General Tax Law (Ley 58/2003) adds a surcharge (recargo) when you file late without a prior requirement from the tax authority. A prior requirement is any administrative action, with your formal knowledge, aimed at checking, inspecting or assessing the debt.
Within the first 12 months, the surcharge is 1% plus 1% for each full month of delay. It is calculated on the amount to pay, and it excludes penalties and late-payment interest accrued until filing.
At 12 months or more the surcharge is 15%, and late-payment interest runs from the day after those 12 months until filing.
The surcharge drops by 25% when two conditions are met. Pay the whole tax due on the late return when you file it. Then pay the rest of the surcharge within the payment period opened by its notice.
Arriving in Spain in 2026?
Your first Spanish tax year starts with a day count. Stay more than 183 days in the calendar year and you are a Spanish tax resident. Residence covers the whole calendar year, so a mid-year move does not split the year in two.
Planning to opt for the Beckham regime? You exercise the option by filing the communication form, Modelo 149. For moves from 16 December 2023 onwards, you have six months from the activity start date. The 183-day guide covers the residency test; the Beckham Law guide covers who qualifies.
Key dates at a glance
These are the dates the official texts give. The next campaign will have its own order.
Photo credits
- A Valencia city square, shown for atmosphere: Wikimedia Commons (opens in a new tab), Zarateman (CC0)
Step by step
- Check the income limitsGross employment income up to €22,000 from one payer needs no return; €15,876 applies with several payers or a payer not obliged to withhold; registered autónomos always file.
- Pay the second instalmentIf you split the 2025 payment and did not debit the second part, pay the remaining 40% with Modelo 102 by 5 November 2026.
- File the quarterly returns if you are an autónomoModelo 130 for the first three quarters runs from the 1st to the 20th of April, July and October. Modelo 303 for the third quarter of 2026 is due by 20 October.
- Report foreign assetsIf you are obliged to file Modelo 720 or 721, file between 1 January and 31 March of the year after the one reported.
- File late rather than not at allWithout a prior requirement, the surcharge is 1% plus 1% for each full month of delay, and 15% at 12 months or more.
Not confirmed: Tax year 2026 dates are not published; watch the Tax Agency campaign page. The order allows direct debit to 2 November 2026 while the calendar gives earlier cut-offs, so pay with Modelo 102 by 5 November. The Modelo 130 window for the fourth quarter, 1 to 30 January, is not on the Tax Agency calendar; check it in January.
Reach readers planning life in Valencia. Advertise → hello@settlevalencia.com
Common questions
Can I still file the Renta 2025 return?
The ordinary window closed on 30 June 2026. A late return is still filed; without a prior requirement from the tax authority, it carries a surcharge of 1% plus 1% for each full month. At 12 months or more the surcharge is 15%.
When is the 40% second payment due?
If you split the payment of the 2025 return, the remaining 40% is due by 5 November 2026, inclusive. Unless it is debited, pay it with Modelo 102, electronically or at a bank office in Spain. The split needs a return filed inside the ordinary period.
Do I have to file if my only income is a foreign pension?
For a Spanish tax resident, the limit is €15,876 when the payer is not obliged to withhold, which covers a foreign pension payer. Over the limit, you file. You also file in any case if you are entitled to the international double taxation deduction.
Do autónomos file Modelo 130 every quarter?
Yes, if you are a businessperson or professional in direct estimation: the IRPF instalment is filed and paid quarterly. Professionals skip the instalment when at least 70% of last year's activity income was withheld. When the calculation gives nothing to pay, a nil return is filed.
When is the Modelo 720 deadline?
Between 1 January and 31 March of the year after the one reported. The 2026 window, for the year before, ran from 1 January to 31 March 2026. If the website fails for technical reasons, four more calendar days apply.
Which date applies to a non-resident's rental income?
Rent of 2026 declared as a group is filed from 1 to 20 April 2027. Rent accrued from July to September 2026 and declared separately is filed in the first 20 calendar days of October 2026. Later rent declared separately follows April 2027.
Can the refund go to a foreign account?
You may ask for the refund by transfer through a financial institution established abroad. Keep the proof of filing: it carries a 16-character verification code with the date and time of filing.
Read next
General information checked against the sources listed above, not legal advice for your situation. Rules and office practice change; confirm with the immigration office or a licensed adviser before you act. See how guides are checked.
Spotted an error? Report it.